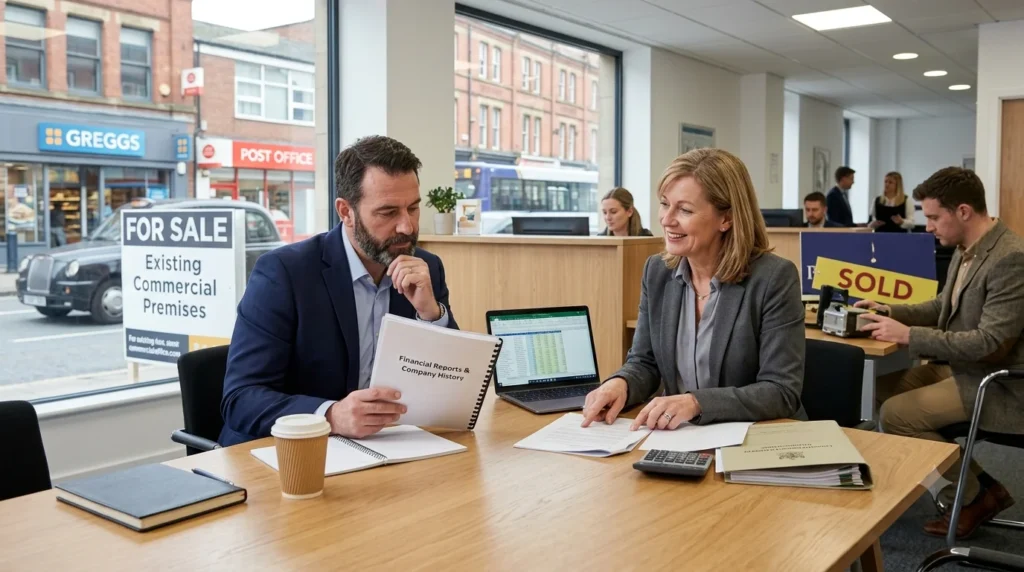
Buying an existing limited company can provide a quicker route into business ownership than launching a new venture from the ground up. The company may already have customers, employees, equipment, supplier agreements, trading history and reliable income.
However, purchasing a limited company also means taking on risks that may not be immediately visible. Outstanding tax, legal disputes, unpaid suppliers, weak contracts or inaccurate accounts could turn an apparently attractive company into an expensive problem.
The safest approach is to investigate the business thoroughly, agree suitable protections and obtain professional legal and financial advice before completing the purchase.
Can You Buy an Existing Limited Company in the UK?
Yes, an individual, another company or a group of investors can buy an existing UK limited company. In most cases, the buyer purchases the shares from the existing shareholders. The company continues to operate as the same legal entity, but its ownership changes.
Alternatively, the buyer can purchase selected assets from the company rather than buying its shares. These assets might include its equipment, customer database, intellectual property, stock, website and trading name.
This distinction is important because it determines what the buyer acquires and which liabilities may come with the transaction.
| Purchase structure | What the buyer acquires | Main consideration |
| Share purchase | Shares in the complete limited company | The company retains its assets, contracts and liabilities |
| Asset purchase | Selected assets and parts of the business | Individual contracts, licences and assets may need transferring |
| Management buyout | Existing management buys the company | Funding and management responsibilities must be carefully planned |
| Management buy-in | An external management team buys the company | The incoming team must understand the business and its market |
A share purchase is generally what people mean when discussing how to buy a limited company in the UK.
What Is the Difference Between Buying a Company and Starting One?
Starting a company allows its founders to create their own brand, processes and business model. It may cost less initially, but building a customer base and establishing regular income can take considerable time.
Buying an existing company provides access to an established operation. The buyer could receive immediate turnover, trained employees, supplier relationships and an existing reputation.
It may therefore be attractive to someone who wants to avoid the earliest and most uncertain stage of business development.
However, an existing business usually costs more than forming a new company. The buyer must also work within an established structure and deal with any problems left by the previous owners.
Entrepreneurs comparing both routes should consider whether they would prefer to buy and sell business ideas or build an entirely new operation around their own plans.
Should You Buy the Shares or the Business Assets?
Choosing between a share purchase and an asset purchase is one of the most important decisions in the transaction.
How Does a Share Purchase Work?
In a share purchase, the buyer acquires shares from one or more existing shareholders. If the buyer purchases all the issued shares, they obtain complete ownership of the company.
The limited company itself does not disappear or become a newly incorporated business. It normally keeps its company number, trading history, assets, employees and contractual relationships. This continuity can make the transaction easier from an operational perspective.
The disadvantage is that the company also retains its liabilities. These could include tax obligations, employment claims, customer complaints, debts, legal disputes and contractual commitments.
How Does an Asset Purchase Work?
An asset purchase allows the buyer to select which parts of the business they want. For example, the buyer could purchase the machinery, stock, domain name, customer relationships and intellectual property without acquiring the company that owns them.
This structure can provide greater control over which liabilities are accepted. However, transferring every necessary asset and contract can be complicated. Landlords, customers, suppliers, lenders and regulators may need to provide consent.
Employee transfer rules may also apply. Specialist advice is particularly important where staff will move from the seller’s company to the buyer’s business.
How Do You Find a Limited Company to Buy?
Companies for sale can be found through business brokers, accountants, solicitors, commercial finance professionals and specialist marketplaces. Buyers can also approach owners directly when they identify a business that suits their plans.
An off-market approach may provide access to companies that have not been publicly advertised. However, the buyer should make the approach discreetly, as employees, customers and suppliers may not know that the owner is considering a sale.
Before beginning the search, the buyer should establish clear criteria covering:
- Preferred industry and location
- Maximum investment budget
- Minimum turnover or profit
- Number of employees
- Level of owner involvement
- Assets and licences required
- Acceptable level of debt
- Potential for future growth
These criteria help the buyer avoid wasting time on companies that do not support their experience, budget or long-term objectives.
How Should You Value an Existing Limited Company?
A seller’s asking price should not automatically be treated as the company’s true market value. The valuation must be supported by its financial performance, assets, risks and future prospects.
Common valuation methods include a multiple of maintainable earnings, discounted future cash flow, asset-based valuation and comparisons with similar business sales. Different methods can produce significantly different results, so more than one calculation may be required.
The valuation should consider:
| Valuation factor | What the buyer should examine |
| Revenue | Whether income is stable, recurring and accurately recorded |
| Profit | Whether reported profit can continue after the owner leaves |
| Assets | The condition and realistic resale value of business assets |
| Liabilities | Borrowing, unpaid tax, leases, claims and supplier balances |
| Customers | Whether revenue depends heavily on one or two customers |
| Contracts | The length, profitability and transferability of agreements |
| Intellectual property | Ownership and commercial importance of brands, software or designs |
| Market position | Competition, reputation and future demand |
| Owner dependence | Whether the company can operate without the seller |
The buyer should also adjust the figures for exceptional expenses, personal costs paid through the business and an unrealistically low owner’s salary. This helps reveal the company’s maintainable profit under new ownership.
What Financial Due Diligence Should Be Completed?
Financial due diligence tests whether the seller’s claims are supported by reliable records. An accountant should normally review at least the latest available accounts, management figures and underlying transaction records.
The review should cover turnover, gross margins, operating expenses, cash flow, borrowing, tax liabilities, debtor balances and unpaid suppliers. Bank statements should be compared with the figures shown in the accounting records.
Particular attention should be given to unusual transactions before the sale. A temporary reduction in expenses or a large one-off order could make recent performance appear stronger than it really is.
The buyer should also check:
- Whether customers pay on time
- Whether stock is usable and correctly valued
- Whether equipment requires replacement
- Whether any loans carry personal guarantees or security
- Whether Corporation Tax, PAYE and VAT records are complete
- Whether directors have taken money from the company
- Whether future orders are confirmed or merely expected
Understanding the company’s bookkeeping system is essential after completion. Reviewing suitable small business accounting software can help the new owner improve financial reporting and control.
What Legal Due Diligence Is Required?
Legal due diligence looks for obligations, ownership problems and disputes that may reduce the company’s value.
The buyer’s solicitor should check the company’s articles of association, shareholder records, statutory registers, previous share issues, board minutes and Companies House filing history.
They should confirm that the seller legally owns the shares and has the authority to sell them.
Commercial contracts must also be reviewed. Some agreements contain change-of-control provisions allowing a customer, supplier, landlord or lender to terminate the contract when the company is sold.
Other areas to examine include:
- Employment contracts and workplace disputes
- Property leases and planning restrictions
- Intellectual property ownership
- Data protection procedures
- Regulatory permissions and licences
- Insurance policies and previous claims
- Customer complaints and refund obligations
- Current or threatened legal proceedings
- Guarantees provided by the company
Working with the right adviser can prevent important risks from being missed. The guide to choosing a business solicitor explains what to consider when selecting legal support.
What Is a Non-Disclosure Agreement?
A non-disclosure agreement, commonly called an NDA, is normally signed before the seller releases confidential information.
It prevents the prospective buyer from improperly using or sharing information about customers, finances, suppliers, employees and business processes. This is particularly important if the buyer already operates in the same industry.
The NDA should explain what information is confidential, how it may be used, who can access it and what must happen if the transaction does not proceed.
Signing an NDA does not commit the buyer to purchasing the company. It simply establishes how sensitive information will be handled during discussions.
What Should Be Included in the Heads of Terms?
Heads of terms record the main commercial points that the buyer and seller have agreed in principle. They are usually prepared before detailed due diligence and the final purchase agreement.
The document may cover the proposed price, payment structure, transaction type, exclusivity period, due diligence process and expected completion date. It may also explain whether the seller will remain involved during the handover.
Most commercial provisions in heads of terms are not intended to be legally binding, although confidentiality, exclusivity and cost provisions may be binding. Both parties should obtain legal advice before signing.
The heads of terms should be sufficiently detailed to reduce later disagreements but flexible enough to allow the deal to change if due diligence reveals new information.
How Can You Finance the Purchase?
A company purchase can be financed using personal funds, investor capital, commercial borrowing, seller finance or a combination of these methods.
Seller finance allows part of the price to be paid after completion. The unpaid amount may be settled through instalments or deferred until an agreed date. An earn-out is another arrangement under which part of the price depends on the company meeting future performance targets.
Each structure has advantages and risks. Borrowing provides immediate funds but creates repayment obligations. Deferred consideration reduces the buyer’s initial cash requirement but may lead to disagreements about payment conditions.
Anyone considering external funding should compare business loan options and calculate whether the company can meet repayments without restricting working capital.
The buyer must budget for more than the purchase price. Legal fees, accountancy costs, tax, finance fees, insurance, working capital and immediate investment may all increase the total amount required.
What Is Included in a Share Purchase Agreement?
The share purchase agreement, or SPA, is the main legal contract between the buyer and seller. It sets out what is being purchased, how much will be paid and what must happen before and after completion.
The agreement normally contains warranties from the seller about the company’s accounts, tax position, assets, employees, contracts and legal compliance. If an important warranty later proves to be untrue, the buyer may be able to pursue a contractual claim.
An indemnity can provide more specific protection against an identified risk. For example, the seller might indemnify the buyer against a particular tax investigation or unresolved legal claim.
The agreement may also contain restrictive covenants preventing the seller from immediately establishing a competing business, approaching important customers or recruiting key employees. These restrictions must be carefully drafted to remain reasonable and enforceable.
What Happens on Completion?
Completion is the stage at which ownership transfers and the buyer becomes the company’s new shareholder.
The parties sign the final agreements and complete the required share transfer documents. The purchase money is paid according to the agreed structure, and the seller provides the company records, share certificates, passwords, banking information and other completion materials.
Depending on the transaction, completion may also involve:
- Appointing new directors
- Accepting outgoing director resignations
- Updating the register of members
- Issuing new share certificates
- Updating people with significant control information
- Changing the registered office
- Transferring banking authority
- Notifying insurers and important contract partners
- Paying any applicable Stamp Duty
The company’s internal records and required Companies House information must be updated correctly. The buyer should not assume that signing the purchase agreement automatically completes every administrative requirement.
What Should the New Owner Do After Buying the Company?
The first few months after completion can determine whether the acquisition succeeds. The new owner should have a transition plan prepared before the deal closes.
Employees need clear communication about leadership, responsibilities and immediate priorities. Key customers and suppliers should also receive appropriate reassurance, especially when their relationships were closely connected to the former owner.
The buyer should protect cash flow, monitor customer retention and avoid changing every part of the company at once. Rapid changes can unsettle employees and damage the qualities that originally made the business attractive.
A practical post-acquisition plan should cover financial controls, staff retention, customer communication, supplier continuity, technology access, regulatory compliance and performance targets.
Although the buyer is entering the business, it is also worth considering the eventual departure from it. Understanding how to plan a business exit can influence decisions about ownership, investment and long-term value from the beginning.
What Are the Biggest Risks of Buying an Existing Company?
The greatest risk is paying for a company without fully understanding what sits behind its revenue and reputation.
A business may appear profitable because the owner works excessive hours, takes a low salary or relies on a single long-standing customer. Its contracts may be informal, its intellectual property may belong to a third party, or important employees may intend to leave after the sale.
Hidden liabilities are another concern in a share purchase. The buyer owns the company after completion, but the company remains responsible for its existing obligations.
No amount of paperwork can eliminate every commercial risk. However, independent due diligence, realistic valuation and properly drafted contractual protections can substantially reduce the likelihood of an unpleasant surprise.
Is Buying an Existing Limited Company Worth It?
Buying an existing limited company can be worthwhile when the business has dependable earnings, transferable customer relationships, capable employees and genuine growth potential. It can provide a much faster route to trading than building an operation from nothing.
The purchase should not proceed simply because the company is available or appears affordable. The buyer must understand exactly what is being acquired, how the valuation was calculated and which liabilities will remain after completion.
A good acquisition is one that continues to make commercial sense after its risks, funding costs and required investment have been included.
Conclusion
Buying an existing limited company in the UK involves much more than agreeing a price with its owner. The buyer must select the correct purchase structure, value the business, arrange finance, investigate its records and negotiate suitable legal protections.
A share purchase offers continuity but can expose the buyer to existing liabilities. An asset purchase may offer greater flexibility but can require individual assets and agreements to be transferred.
Whichever structure is selected, professional legal and financial due diligence is essential. A careful process gives the buyer the best chance of acquiring a stable company that can continue growing under new ownership.
Frequently Asked Questions
Can one person buy an entire limited company?
Yes. One individual can purchase all the shares in a private limited company and become its sole shareholder. They may also become a director, although ownership and directorship are separate roles.
Do you inherit debt when buying a limited company?
In a share purchase, the company retains its existing debts and liabilities after its ownership changes. An asset purchase may allow the buyer to avoid certain liabilities, depending on the agreement and applicable law.
How long does it take to buy an existing company?
The timeframe depends on the company’s size, record quality, funding arrangements and transaction complexity. A straightforward purchase may be completed relatively quickly, while a regulated or complicated business can require several months.
Do you need a solicitor to buy a company?
There is no simple rule requiring every buyer to appoint a solicitor, but completing a company acquisition without specialist legal advice is extremely risky. The solicitor checks ownership, prepares agreements and helps protect the buyer against hidden liabilities.
Is Stamp Duty payable when buying a UK limited company?
Stamp Duty may be payable when shares are purchased using a stock transfer form, depending on the transaction value and whether any exemption or relief applies. The buyer should confirm the current treatment with a qualified adviser.
Can the company keep its existing name after the sale?
Yes. A share purchase does not automatically change the company’s registered or trading name. The new owner can normally continue using it, provided the company owns the relevant brand and intellectual property rights.
Blogger & Content creator | An insightful writer sharing practical advice for UK entrepreneurs