How To Value A Business In The UK?

UK Startup Blog Archive
Table of Contents
Knowing how to value a business gives you a clearer idea of what your company may be worth to a buyer, investor or shareholder. There is no single formula that works for every UK business.
The most suitable approach depends on profitability, assets, cash flow, growth prospects, industry conditions and the reason for carrying out the valuation.
For an established profitable company, valuation may start with maintainable earnings or adjusted EBITDA and an appropriate multiple.
An asset-heavy company may be better assessed through its net assets, while an early-stage startup with little profit may require revenue, recurring income, comparable transactions or investor-focused valuation methods.
A reliable valuation therefore looks beyond turnover alone and considers both the financial performance of the business and the risks a potential buyer would inherit.
Why Is It Important To Know What Your Business Is Worth?
A business valuation is useful long before you decide to sell.
Understanding what drives the value of your company can help you identify weaknesses, prepare for investment, negotiate with shareholders and make better decisions about future growth.
You may need a valuation when raising finance, selling some or all of the company, bringing in investors, planning an exit or dealing with a shareholder transaction.
Buyers can also use valuation methods when deciding whether the asking price for an existing company is reasonable.
Anyone considering whether to buy a limited company should therefore look beyond its stated selling price and examine earnings, liabilities, assets, contracts and future prospects.
A valuation is also useful as an internal benchmark.
If a company becomes less dependent on its founder, improves margins and develops predictable recurring revenue, its value may rise even if turnover does not increase dramatically.
The important point is that business value and annual sales are not the same thing.
Two companies with identical turnover can have significantly different values because their profitability, risk and future earning potential are different.
How Do You Calculate The Value Of A Business?
A practical business valuation normally begins by establishing the financial performance that a new owner could reasonably expect the company to maintain.
For an established SME, the process may look like this:
- Review Maintainable Earnings: Examine recent accounts and management information to determine whether current profits are sustainable.
- Normalise the Financial Figures: Remove genuine one-off costs or income and adjust owner-related expenses where appropriate.
- Apply a Suitable Valuation Method: This could involve an earnings multiple, discounted cash flow, asset valuation, revenue multiple, or comparable-company approach.
- Adjust for Cash, Debt, and Other Items: Depending on the valuation basis, surplus cash, borrowings and debt-like liabilities may need to be reflected before determining the value attributable to shareholders.
Historic accounts are important, but buyers usually care about what the company can generate in the future. Forecasts therefore need realistic assumptions about sales, margins, employees, investment and working capital.
This is one reason accurate financial forecasts matter when preparing a business plan.
Forecasts built on unsupported growth assumptions can produce an unrealistic valuation, particularly when using a forward-looking method such as discounted cash flow.
How Do You Work Out Adjusted EBITDA Before Valuing A Business?
EBITDA stands for earnings before interest, tax, depreciation and amortisation. It is commonly used as one measure of operating performance when comparing businesses.
For private businesses, valuers may consider adjusted or normalised EBITDA rather than simply taking the figure shown in the accounts.
The aim is to estimate the level of earnings that could reasonably continue under a new owner.
For example:
| Item | Amount |
| Reported EBITDA | £180,000 |
| One-Off Legal Cost Added Back | £12,000 |
| Exceptional Repair Added Back | £8,000 |
| Non-Recurring Income Removed | £5,000 |
| Adjusted EBITDA | £195,000 |
Not every expense can simply be added back.
Normal wages, rent, software costs, marketing expenditure and other costs required to operate the company generally remain part of the business’s ongoing cost base.
Owner-related adjustments also need care.
If a director receives a salary well above or below the market cost of replacing their role, a purchaser may adjust the figure to reflect the realistic employment cost after acquisition.
Adjusted EBITDA can therefore give a clearer picture of maintainable operating performance, but the adjustments need to be reasonable and supported by evidence.
What Are The Traditional Business Valuation Methods?
Several established methods can be used to calculate the value of a business. The right approach depends on the company and the quality of information available.
Earnings Multiple Valuation
An earnings multiple values the company by applying a multiple to maintainable profit or adjusted EBITDA.
For example, if adjusted EBITDA is £200,000 and an appropriate multiple is 4, the implied enterprise value would be:
£200,000 × 4 = £800,000
The difficult part is not the multiplication. It is determining whether £200,000 represents sustainable earnings and whether a multiple of 4 is justified.
Discounted Cash Flow Valuation
Discounted cash flow, or DCF, estimates the present value of cash the business is expected to generate in future.
Future cash flows are forecast and then discounted because money received several years from now is generally worth less than money available today and carries uncertainty.
DCF can be useful for mature businesses with relatively predictable cash flows, although the final figure can change significantly when assumptions about growth, margins or the discount rate are altered.
Asset-Based Valuation
Asset valuation looks at what the business owns and owes.
This can include property, machinery, stock, vehicles, equipment and certain intangible assets, less liabilities.
The approach may be particularly relevant to property, manufacturing or other asset-heavy businesses.
It can be less suitable on its own for companies whose main value comes from people, technology, brand, customers or future earnings.
Revenue Multiple Valuation
A revenue multiple applies a multiplier to turnover rather than profit.
For example:
Annual Revenue × Appropriate Revenue Multiple = Indicative Business Value
Revenue multiples can sometimes be useful where profits are currently low but the company is growing quickly. However, turnover alone does not show whether the company makes money.
A £2 million turnover company earning £50,000 may be less attractive than a £1 million turnover company producing £250,000 of sustainable profit.
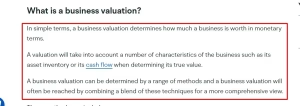
The British Business Bank sets out established approaches including discounted cash flow, asset valuation, times revenue, comparable analysis and precedent transactions.
What Are The Newer Methods Used To Calculate The Value Of A Business?
Some valuation approaches have become more prominent as technology companies, subscription businesses and early-stage startups have grown.
They are not all newly invented methods, but they are increasingly important when traditional profit-based calculations do not capture how a modern business operates.
Adjusted EBITDA Multiples
Instead of relying on reported accounting profit, buyers may value established private businesses using normalised EBITDA and a market-based multiple.
This allows unusual expenses, owner-specific costs and one-off events to be considered before determining maintainable earnings.
Recurring Revenue And ARR Multiples
Subscription-based businesses may be assessed using recurring revenue metrics such as Annual Recurring Revenue, commonly called ARR.
The quality of that recurring revenue matters.
A company with strong retention, predictable renewals and diversified customers may be viewed differently from one where customers can leave quickly or a few clients generate most of the income.
Comparable Transaction Valuation
Recent acquisitions of similar businesses can provide evidence of what buyers have actually been prepared to pay.
Relevant transactions need to be genuinely comparable. Size, profitability, geography, growth and market conditions can all affect the multiple paid.
Venture And Startup Valuation Methods
Very early-stage companies may have little revenue and no meaningful profit, making an EBITDA multiple unsuitable.
Investors may instead consider the market opportunity, traction, intellectual property, founding team, comparable funding rounds, expected exit value and the percentage ownership required for the investment.
These approaches involve considerably more judgement than valuing an established company with years of profitable trading.
Which Business Valuation Method Should You Use?
There is no universally correct method. The company’s stage, industry and financial characteristics should influence the approach.
| Type Of Business | Possible Starting Approach |
| Established Profitable SME | Adjusted Earnings Or EBITDA Multiple |
| Asset-Heavy Company | Asset-Based Valuation |
| Stable Cash-Generating Business | DCF And Earnings Methods |
| Subscription Or SaaS Business | ARR, Revenue And Earnings Metrics |
| Early-Stage Startup | Investor, Revenue Or Comparable Approaches |
| Loss-Making Company | Assets, Revenue, Comparables Or Strategic Value |
Using more than one method can also be useful.
For example, you might calculate an earnings-based value and then compare the result with recent transactions involving similar companies.
If the figures are very different, the assumptions behind each calculation should be examined rather than simply choosing the higher valuation.
What Factors Increase Or Reduce The Value Of A Business?
A valuation multiple reflects more than financial performance. Buyers are also assessing how risky the future earnings are.
A company may command a stronger valuation when it has predictable income, good margins, low customer concentration and a management team capable of operating without constant involvement from the founder.
Factors that can support a stronger valuation include:
- Recurring Revenue – Predictable subscriptions or contracted income can improve visibility over future cash flow
- Diversified Customers – Losing one customer has less impact when revenue is spread across a broad customer base
- Strong Management – A capable management team reduces dependence on the owner
- Consistent Growth – Sustainable growth in sales and earnings may increase buyer confidence
Factors that may reduce value include heavy reliance on one customer, declining margins, unresolved disputes, poor financial records, excessive debt or dependence on the founder for day-to-day operations.
Goodwill and intangible assets can also matter.
A recognised brand, proprietary software, patents, trademarks, customer relationships and valuable contracts can make a business more attractive even though these assets may not be fully reflected in its physical asset base.
What Does A Business Valuation Calculation Look Like In Practice?
Consider an established UK business with the following illustrative figures:
| Calculation | Amount |
| Reported EBITDA | £170,000 |
| Valid Normalisation Adjustments | £20,000 |
| Adjusted EBITDA | £190,000 |
| Illustrative Multiple | 4.5× |
| Enterprise Value | £855,000 |
| Surplus Cash | £55,000 |
| Debt | £110,000 |
| Illustrative Equity Value | £800,000 |
The initial calculation is:
£190,000 × 4.5 = £855,000 Enterprise Value
If the transaction assumes surplus cash is added and debt is deducted:
£855,000 + £55,000 − £110,000 = £800,000 Equity Value
This does not mean every company producing £190,000 of EBITDA is worth £855,000.
A buyer may apply a higher or lower multiple after considering growth, customer concentration, management, competitive position, contracts and sector conditions.
The example simply shows how earnings, multiples, cash and debt can interact in a valuation.
What Is The Difference Between Enterprise Value And Equity Value?
Enterprise value and equity value are often confused, particularly when a business owner hears that their company is “worth £1 million”.
Enterprise value generally represents the value of the underlying operating business before considering how it is financed.
Equity value represents the value attributable to the shareholders after relevant cash, borrowings and other agreed adjustments are taken into account.
A simplified calculation can be expressed as:
Equity Value = Enterprise Value + Surplus Cash − Debt
Actual transactions can be more complicated. Buyers and sellers may also negotiate adjustments relating to working capital, debt-like liabilities, unpaid tax, director loans or other balance-sheet items.
This distinction matters when selling a company because the headline valuation does not necessarily equal the amount ultimately received by its owners.
How Do You Value A Startup With Little Or No Profit?
Traditional earnings multiples become difficult to use when a startup has not yet reached profitability.
Instead, founders and investors may look at how quickly the business is growing, its addressable market, revenue quality, customer acquisition, technology, intellectual property and the likelihood of reaching future profitability.
For a subscription startup, recurring revenue and retention may be particularly important.
For a pre-revenue technology company, investors may place greater weight on the product, intellectual property, team, market opportunity and evidence of customer demand.
Funding also affects valuation because investors normally consider both the amount being invested and the equity they receive.
Founders exploring ways to get money to start a business should therefore understand that raising equity finance involves not only finding capital but agreeing what the company is worth before and after the investment.
Startup valuation is naturally more uncertain than valuing a mature company. Forecasts should therefore be supported with evidence wherever possible rather than assuming aggressive growth simply to justify a higher figure.
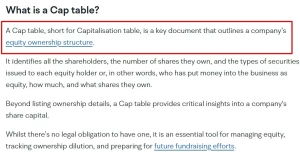
The British Business Bank explains pre-money valuation, post-money valuation and price-per-share in the context of startup ownership and funding.
How Can You Increase The Value Of Your Business Before Selling?
Increasing business value usually takes more than cutting costs immediately before a sale. Buyers generally want evidence that improvements are sustainable.
Reducing reliance on the founder is one important step. If customers, suppliers and employees depend entirely on one person, a purchaser may see a greater risk when ownership changes.
Businesses can also strengthen their position by improving financial records, protecting intellectual property, documenting processes and reducing customer concentration.
Where possible, focus on changes that make future income more predictable:
- Strengthen Recurring Income – Develop contracts, subscriptions or repeat-customer relationships where appropriate
- Improve Profitability – Review margins and remove inefficient costs without damaging future growth
- Build Management Depth – Give capable employees clear responsibility for important functions
- Reduce Concentration Risk – Avoid becoming overly dependent on a single customer, supplier or sales channel
Preparing early is important. Exit planning for entrepreneurs can involve reviewing business assets, ownership arrangements and liquidity well before a transaction becomes imminent.
A stronger business is generally easier to value because prospective buyers have more reliable evidence of what they are acquiring.
Frequently Asked Questions
How Much Is My Business Worth?
Your business is worth what a willing buyer is prepared to pay, supported by factors such as maintainable earnings, assets, growth, risk, cash flow and comparable transactions.
How Many Times Profit Is A Business Worth?
There is no fixed profit multiple for every business. The appropriate multiple depends on the industry, size, growth, recurring income, risk and quality of the company’s earnings.
Can You Value A Business Based On Turnover?
Yes, revenue multiples are sometimes used, particularly for high-growth or early-stage companies. However, turnover alone does not show profitability or cash generation.
Can I Value My Own Business?
You can calculate an indicative valuation using earnings, assets, cash flow and comparable businesses. A professional valuation may be preferable where substantial money, tax, investment or a dispute is involved.
What Is The Most Accurate Business Valuation Method?
No single method is always the most accurate. Established companies may suit earnings or DCF approaches, while asset-heavy businesses and startups may require different methods.
Does Business Debt Reduce Its Value?
Debt can affect the amount attributable to shareholders. When moving from enterprise value to equity value, relevant borrowings are commonly considered alongside cash and other balance-sheet adjustments.
How Often Should A Business Be Valued?
There is no compulsory timetable for ordinary business planning. However, reviewing value periodically and before investment, a sale, restructuring or major ownership change can help owners make better-informed decision.
Blogger | Business Writer | Sharing startup advice on UK business blogs
Related Articles in Startup
View All →
Newscivil Com: Can This Digital News Platform Help UK Startups Spot Emerging Trends?
For startup founders, staying informed is no longer simply about reading the business pages each morning. Artificial intelligence, changing consumer habits, technology developments, government decisions and wider social…
Meet the Startup Turning Screen Time Into a New Way to Make Money
Britain does not exactly have a shortage of side hustles. You can deliver takeaways, sell clothes online, start freelancing, walk dogs, tutor in the evenings or attempt to…
8 Best Coworking Spaces for Bootstrapped London Startups to Launch and Scale in 2026
Bootstrapped founders don’t have the luxury of a fitted-out HQ from day one. What you need is a London coworking space that flexes with you: a hot desk…