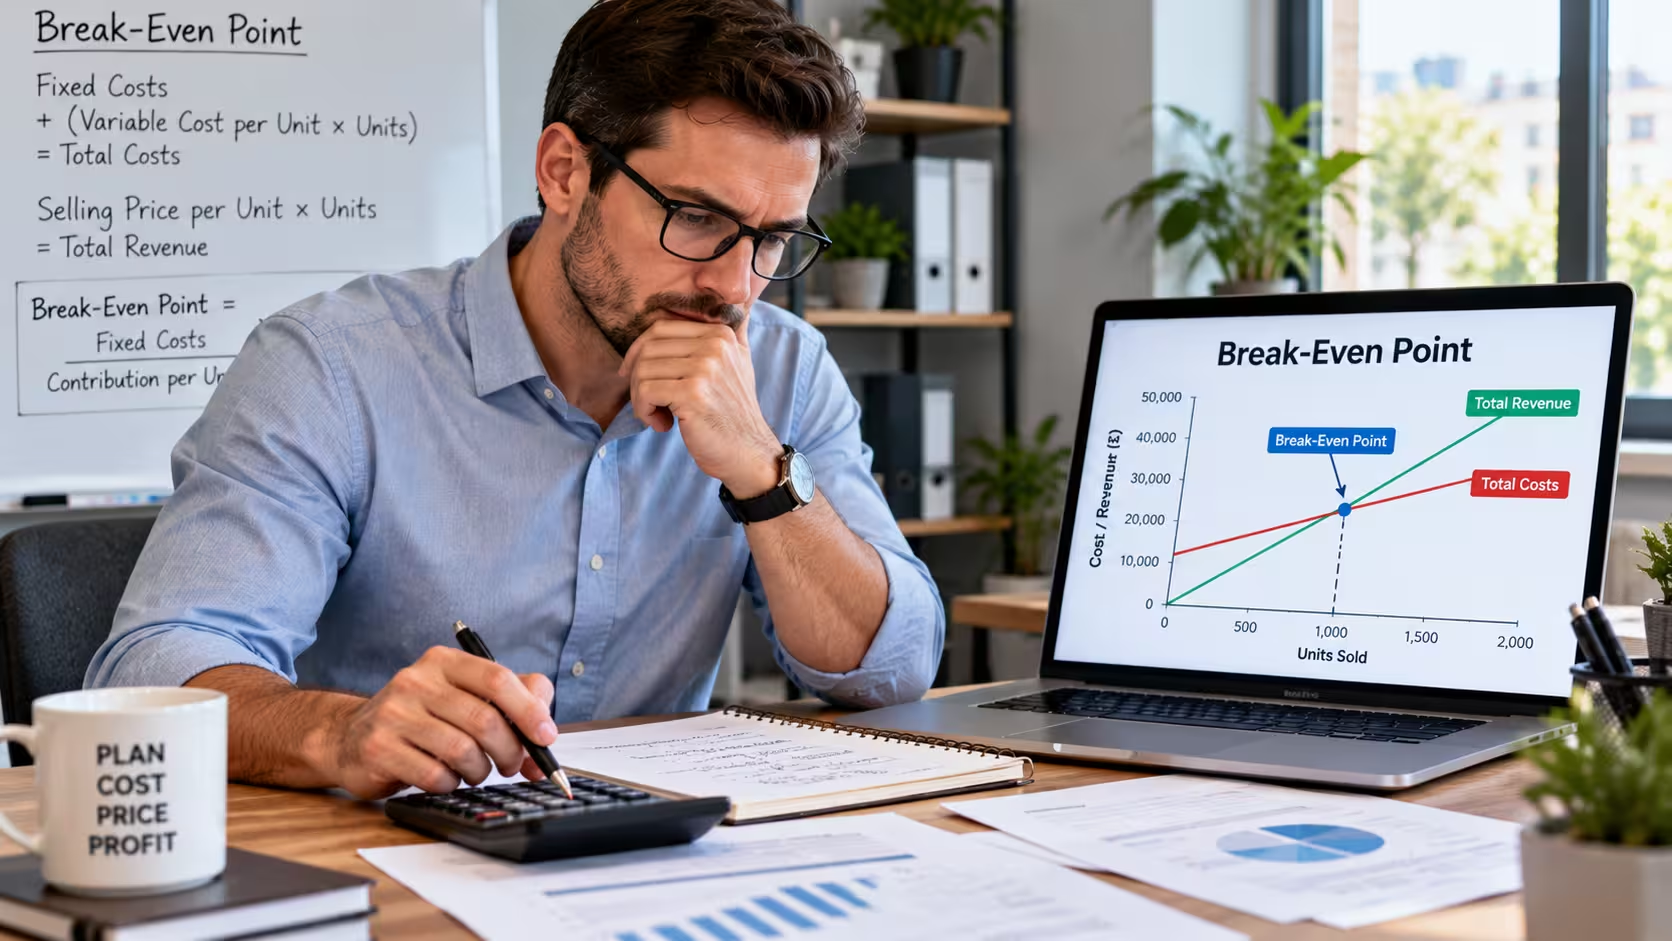
How To Work Out Break-Even Point For A Business?

UK Startup Blog Archive
Table of Contents
Knowing how to work out the break-even point can help a business understand how much it needs to sell before it begins making a profit.
It is particularly useful for startups because early-stage businesses often need to control costs carefully while testing prices and forecasting demand.
Break-even analysis compares revenue with fixed and variable costs. Once total revenue equals total costs, the business has reached its break-even point. Sales above this level can contribute towards profit, while sales below it normally result in a loss.
For businesses planning their finances in 2026, break-even analysis can also help with pricing decisions, cost increases, sales targets and cash-flow planning.
What Does Break-Even Point Mean?
The break-even point is the level of sales at which a business’s total revenue exactly covers its total costs.
At break-even:
- Revenue Equals Total Costs
- The Business Makes No Profit
- The Business Makes No Loss
Suppose a business spends £8,000 each month and generates exactly £8,000 after accounting for the relevant sales and variable costs. It has effectively reached break-even for that period.
The concept becomes more useful when businesses calculate how many products, customers, subscriptions or billable hours are required to reach this position.
A startup can use its break-even point when setting sales targets, reviewing prices or deciding whether its current business model is financially realistic.
What Is The Break-Even Point Formula?
The most common formula calculates how many units a business must sell.
Break-Even Point In Units = Fixed Costs ÷ Contribution Per Unit
Contribution per unit is calculated as:
Contribution Per Unit = Selling Price Per Unit − Variable Cost Per Unit
For example, imagine a business has:
| Item | Amount |
| Fixed Costs | £12,000 |
| Selling Price Per Unit | £50 |
| Variable Cost Per Unit | £30 |
| Contribution Per Unit | £20 |
The calculation is:
£12,000 ÷ £20 = 600 units
The business must therefore sell 600 units to break even.
It is important not to describe 600 units as £600 of revenue. The result of this formula represents units sold.
Break-even revenue can then be calculated by multiplying the break-even units by the selling price.
600 × £50 = £30,000
The business therefore needs £30,000 of sales revenue at those prices and costs to reach break-even.
Businesses can also calculate break-even revenue directly by using the contribution margin ratio.
Contribution Margin Ratio = Contribution Per Unit ÷ Selling Price Per Unit
In this example:
£20 ÷ £50 = 40%
Break-even revenue is:
£12,000 ÷ 40% = £30,000
Both methods should produce the same result when the underlying assumptions are consistent.
How To Work Out Break-Even Point Step By Step?
A reliable break-even calculation starts with accurate costs rather than simply entering numbers into a formula.
1. Choose The Period
Decide whether the calculation relates to a week, month, quarter or year.
Costs and sales figures should cover the same period. Comparing monthly fixed costs with annual revenue would produce a misleading result.
2. Identify Fixed Costs
Fixed costs generally do not change directly with each additional unit sold.
Typical examples may include:
- Office Or Shop Rent
- Business Insurance
- Software Subscriptions
- Permanent Staff Costs
- Accounting Fees
A business should include all relevant fixed costs rather than only the most obvious expenses.
3. Calculate Variable Costs
Variable costs increase as sales or production increase.
They may include raw materials, packaging, transaction charges, delivery costs or commissions.
4. Identify The Selling Price
Use the realistic selling price rather than an ideal price that customers are unlikely to pay.
Discounts and promotional pricing should also be considered if they form a regular part of the business model.
5. Calculate Contribution
Subtract the variable cost per unit from the selling price.
If a product sells for £40 and costs £16 to produce and fulfil, its contribution is:
£40 − £16 = £24
6. Calculate Break-Even
If fixed costs are £9,600:
£9,600 ÷ £24 = 400 units
The business needs to sell 400 units to reach break-even.
Where the result includes part of a unit, businesses normally need to round up because they cannot sell a fraction of a physical product.
Break-Even Point Example For A UK Startup
Consider a small UK online business selling reusable drinks bottles.
The business has monthly fixed costs of £4,500.
Each bottle sells for £30 and costs £12 to manufacture, package and fulfil.
Contribution per bottle is:
£30 − £12 = £18
Break-even units are:
£4,500 ÷ £18 = 250 bottles
The startup therefore needs to sell 250 bottles each month before it covers its fixed and variable costs.
Its break-even sales revenue would be:
250 × £30 = £7,500
If the company sells 300 bottles, it has sold 50 units beyond break-even.
Those additional sales contribute towards profit, although the business still needs to consider any additional expenses not included in its original calculation.
This is why accurate cost classification is important. Missing costs can make a business appear more profitable than it really is.
How Does A Break-Even Chart Work?
A break-even chart provides a visual representation of the relationship between sales, costs and revenue.
The horizontal axis normally represents the number of units sold, while the vertical axis represents money.
A basic break-even chart includes a fixed cost line, total cost line and sales revenue line.
The total cost line starts from the level of fixed costs because those costs exist even if no products are sold.
The revenue line usually begins at zero and increases as more products or services are sold.
The point where the revenue line crosses the total cost line is the break-even point.
Before this point, total costs are higher than revenue, meaning the business is operating at a loss.
After the intersection, revenue is higher than total costs, creating the potential for profit.
Break-even charts are useful because they make it easier to see how changes in sales, pricing or costs could affect profitability.
What Is The Margin Of Safety?
The margin of safety measures how far actual or expected sales are above the break-even point.
The formula is:
Margin Of Safety = Actual Or Forecast Sales − Break-Even Sales
Suppose a business expects to sell 900 units and its break-even point is 650 units.
Its margin of safety is:
900 − 650 = 250 units
The company could therefore experience a reduction of 250 units from its expected sales before reaching break-even.
A higher margin of safety generally provides more protection against weaker-than-expected demand.
A very small margin means even a modest fall in sales or rise in costs could push the business into a loss.
For startups, monitoring the margin of safety can therefore be as useful as knowing the break-even point itself.
How Do Price And Cost Changes Affect Break-Even?
The break-even point can move whenever a business changes its prices or experiences a change in costs. Even a relatively small increase in expenses can mean the business needs to make more sales before it starts generating a profit.
| Change In The Business | Impact On Break-Even |
| Higher Selling Price | Usually lowers the break-even point |
| Lower Selling Price | Usually raises the break-even point |
| Higher Fixed Costs | Increases the break-even point |
| Lower Fixed Costs | Reduces the break-even point |
| Higher Variable Costs | Increases the break-even point |
| Lower Variable Costs | Reduces the break-even point |
Consider a business that sells a product for £50. If the variable cost of producing each unit is £30, the contribution per unit is £20.
With fixed costs of £12,000, the break-even point would be:
£12,000 ÷ £20 = 600 units
Now assume the variable cost rises from £30 to £35 because of higher supplier, packaging or delivery costs. The contribution per unit falls from £20 to £15.
The revised calculation becomes:
£12,000 ÷ £15 = 800 units
The business must now sell 800 units instead of 600, meaning it needs 200 extra sales before reaching break-even.
The opposite can happen when a business raises its selling price or reduces costs. A larger contribution from each sale means fewer units are normally required to cover fixed expenses.
Businesses should therefore review their break-even point whenever there is a significant change in rent, wages, supplier prices, delivery charges, production costs or selling prices. This helps keep sales targets realistic and shows whether current pricing still supports profitability.
How Do Service And Subscription Businesses Calculate Break-Even?
Break-even analysis is not limited to businesses selling physical products.
A service company can use billable hours, appointments, projects or clients instead of product units.
Consider a marketing consultant with monthly fixed costs of £3,000.
The consultant charges £75 per billable hour and incurs £15 of variable costs for each billable hour.
Contribution is:
£75 − £15 = £60
The break-even point is:
£3,000 ÷ £60 = 50 billable hours
The consultant therefore needs 50 billable hours each month to cover the relevant costs.
Subscription businesses can use customers or subscriptions as their unit.
Suppose a software startup has monthly fixed costs of £20,000.
Each subscriber generates £40 of monthly revenue and has £10 of variable servicing costs.
Contribution per subscriber is £30.
£20,000 ÷ £30 = 666.67
Because a company cannot normally have a fraction of a customer, it would need at least 667 active subscribers under these assumptions to reach break-even.
For subscription businesses, churn should also be considered because losing customers can push the company back below break-even.
Should VAT Be Included In Break-Even Calculations?
VAT can affect break-even calculations for UK businesses, particularly where the business is VAT registered.
A VAT-registered business should avoid automatically treating the entire VAT-inclusive amount paid by a customer as its own revenue.
For example, if VAT is being collected on behalf of HMRC, that element is generally different from the business’s underlying sales income.
Similarly, recoverable VAT on eligible business purchases may need to be treated differently from costs where VAT cannot be recovered.
The exact treatment depends on the business’s VAT position, its products or services and whether particular amounts are recoverable.
For management calculations, the important principle is consistency. Businesses should avoid mixing VAT-inclusive prices with VAT-exclusive costs unless there is a clear reason for doing so.
Startups unsure about the appropriate treatment should confirm their accounting approach before relying on the final break-even figure.
What Is The Difference Between Break-Even And Cash Flow?
Reaching break-even does not automatically mean a business has enough cash in the bank.
Break-even analysis focuses primarily on the relationship between costs and revenue.
Cash flow focuses on when money actually enters and leaves the business.
A company might technically be profitable but still experience a cash shortage if customers take several weeks to pay invoices.
Other causes can include:
- Large Upfront Stock Purchases
- Late Customer Payments
- Loan Repayments
- Tax And VAT Payments
- Equipment Purchases
- Seasonal Drops In Revenue
For example, a company may issue £20,000 of invoices in one month and appear to be above break-even. If customers will not pay those invoices for another 60 days, the company may still struggle to pay salaries and suppliers today.
Startups should therefore use break-even analysis alongside cash-flow forecasts rather than treating the two as interchangeable.
What Are The Benefits And Limitations Of Break-Even Analysis?
Break-even analysis can give business owners a clear numerical sales target.
It can help determine whether a business model appears realistic before large amounts of money are committed.
Businesses can also use it when comparing different prices, evaluating cost increases or deciding whether expanding operations is financially sensible.
The main benefits include:
- Setting Realistic Sales Targets
- Supporting Pricing Decisions
- Understanding Cost Structures
- Testing Different Business Scenarios
- Measuring Margin Of Safety
- Supporting Funding Discussions
However, break-even analysis also relies on assumptions.
It often assumes that selling prices and variable costs remain reasonably stable. In reality, businesses may offer discounts, experience supplier price changes or sell several different products with different margins.
Demand may also change as prices move.
Break-even analysis does not automatically account for cash-flow timing, unexpected expenses or changes in customer behaviour.
For this reason, businesses should treat break-even as a planning tool rather than a guarantee of future profitability.
Conclusion
Understanding how to work out the break-even point gives business owners a clearer view of the level of sales required to cover their costs.
The basic calculation is straightforward, but the quality of the result depends on the accuracy of the figures used. Fixed costs, variable costs, selling prices and the time period should all be identified correctly.
Businesses should also distinguish between break-even units and break-even revenue rather than treating the two as the same figure.
For startups in 2026, break-even analysis can be especially valuable when rising costs, changing prices or uncertain demand make financial planning more difficult.
Combining it with margin of safety calculations, cash-flow forecasting and regular cost reviews provides a much stronger picture of the financial health of a business.
FAQs
How Do You Calculate Break-Even Point In Units?
Divide total fixed costs by the selling price per unit minus the variable cost per unit. The result shows how many units must be sold to cover costs.
How Do You Calculate Break-Even Revenue?
Break-even revenue can be calculated by dividing fixed costs by the contribution margin ratio. It can also be calculated by multiplying break-even units by the selling price per unit.
What Is A Good Break-Even Point For A Startup?
There is no single ideal figure. A lower and achievable break-even point generally gives a startup more flexibility, but it should be assessed alongside demand, margins and available cash.
How Often Should A Business Recalculate Its Break-Even Point?
Businesses should recalculate it whenever significant prices or costs change. Regular monthly or quarterly reviews can also help businesses identify changing financial risks.
Does VAT Affect Break-Even Calculations?
Yes. VAT-registered businesses need to make sure that VAT-inclusive and VAT-exclusive figures are treated consistently when calculating revenue and costs.
Can A Business Break Even But Still Have Cash Flow Problems?
Yes. A company may reach break-even on paper while still waiting for customers to pay invoices or facing large cash payments before revenue is received.
What Happens To Break-Even When Costs Increase?
Higher fixed or variable costs generally increase the break-even point. The business may need to sell more units, increase prices or reduce costs to compensate.
Blogger & Content creator | An insightful writer sharing practical advice for UK entrepreneurs
Related Articles in Finance
View All →
If I Take Home £1,600 a Month, What Is My Salary in the UK?
If an employee takes home £1,600 per month in the UK, their estimated gross salary is approximately £21,780 per year. This is equal to about £1,815 per month…
Why the Two Year Accounts Rule is Not Actually a Rule?
Ask most new business owners when they can first apply for a mortgage and the answer comes back the same way every time: two years of accounts, minimum,…

Snap-on Franchise Cost: Fees, Investment and Earnings
The Snap-on franchise cost in the UK is currently quoted at £166,597 to £168,487 for the franchise investment, with Snap-on stating that a new franchisee may need to…