Stakeholder Engagement Plan 2027: Complete Guide, Template and Examples for UK Businesses

UK Startup Blog Archive
Table of Contents
A stakeholder engagement plan helps businesses identify the people who influence their decisions, understand their expectations and establish a practical strategy for maintaining productive relationships throughout a project.
For UK startups and growing businesses entering 2027, stakeholder engagement is much more than arranging meetings or sending occasional updates. Investors expect financial accountability, employees want clarity, customers demand transparency, and suppliers need reliable commercial commitments.
When these interests are not managed effectively, businesses can experience project delays, additional expenditure, operational disruption and reduced confidence among important partners.
A well-designed stakeholder engagement plan connects communication directly to measurable business outcomes.
It establishes who needs to be involved, when they should participate, what information they require and who is responsible for maintaining the relationship.
Our analysis of established project management frameworks and business planning practices highlights an important distinction: successful stakeholder engagement is not measured by the number of messages a company sends, but by whether those interactions improve decisions, reduce uncertainty and support delivery.
This guide explains how to create a stakeholder engagement plan for 2027, including stakeholder mapping, communication strategies, financial considerations, practical templates, percentage-based assessments and relevant developments from 2026.
What Is a Stakeholder Engagement Plan?
A stakeholder engagement plan is a structured document that explains how an organisation will identify, prioritise, communicate with and involve individuals or groups who can influence a project or are affected by its outcomes.
It is commonly used in business transformation, startup development, investment projects, product launches, construction, technology implementation and organisational change.
The plan typically contains:
- Stakeholder names, groups and responsibilities.
- Business objectives and expected outcomes.
- Stakeholder interests, concerns and expectations.
- Influence, impact and engagement assessments.
- Communication methods and frequency.
- Relationship ownership and decision-making responsibilities.
- Planned consultation and collaboration activities.
- Engagement budgets, milestones and deadlines.
- Performance indicators and review procedures.
- Escalation processes for complaints and disagreements.
The Association for Project Management (APM) recognises stakeholder engagement as a structured process involving identification, analysis, planning and actions intended to influence stakeholders.
However, modern business engagement also requires meaningful two-way communication.
Companies must consider how stakeholders can influence decisions rather than treating engagement as a method of securing agreement with decisions already made.
For example, a technology startup developing financial software may need to engage investors, employees, customers, payment providers, technology partners and relevant regulatory bodies.
Each group has different interests, meaning a single communication strategy is unlikely to meet everyone’s needs.
Businesses developing a broader project stakeholder management plan should therefore connect relationship management with project scheduling, decision-making authority and financial performance.
Why Is a Stakeholder Engagement Plan Important for UK Businesses in 2027?
Stakeholder engagement has a direct relationship with operational efficiency, financial planning and business continuity.
In our assessment, the greatest commercial benefit comes from identifying potential disagreements before they develop into expensive problems.
A supplier may be concerned about payment terms, an investor may question revenue forecasts, or employees may resist changes that affect their responsibilities.
Without structured engagement, these issues can remain unnoticed until the company reaches an important deadline.
| Business area | Potential engagement benefit | Measurable indicator |
| Investor relations | Greater clarity over financial performance | Reporting delivered on time |
| Project management | Earlier identification of obstacles | Milestones completed |
| Employee relationships | Improved understanding of organisational changes | Employee feedback and participation |
| Customer relationships | Better product and service decisions | Customer satisfaction |
| Supplier management | More predictable delivery and commitments | Supplier performance |
| Financial management | Earlier visibility of potential cost overruns | Budget variance |
| Governance | Clearer accountability and decision records | Completed reviews and approvals |
These benefits are particularly relevant to businesses preparing a business plan for expansion or investment.
A company may have a financially attractive growth strategy, but the execution risk can increase substantially if important stakeholders do not understand or support the proposed changes.
How Can Poor Stakeholder Engagement Increase Business Costs?
Consider a hypothetical startup implementing a new inventory management system.
The company’s operating expenditure is £20,000 per month. A supplier integration problem causes a two-week delay.
Using a simplified four-week month, approximately £10,000 of operating expenditure falls within the delayed period.
That amount is not automatically an additional loss because some expenditure would have occurred regardless.
However, extended contractor commitments, temporary systems, additional support requirements and delayed revenue could create genuine incremental costs.
The business should distinguish between:
- Existing expenditure continuing during the delay.
- Additional costs directly caused by the delay.
- Revenue opportunities postponed or lost.
- Contractual penalties or compensation.
- Longer-term effects on customer and supplier relationships.
This is why stakeholder engagement belongs within financial planning and risk management, rather than being treated exclusively as an administrative communication activity.
What Changed in Stakeholder Engagement During 2026?
Businesses preparing stakeholder engagement strategies for 2027 should account for several developments in governance, data protection and project management practices.
Although there is no universal UK law requiring every startup to maintain a formal stakeholder engagement plan, particular legal and contractual obligations may apply depending on the organisation and project.
| Development | Position entering 2027 | Business implication |
| UK Corporate Governance Code | Provision 29 applies to relevant financial years beginning on or after 1 January 2026 | In-scope listed companies must strengthen reporting on the effectiveness of material internal controls |
| Data protection guidance | ICO guidance was updated in October 2026 following changes under the Data (Use and Access) Act | Businesses should review how they collect, use and retain personal stakeholder information |
| Government project delivery | The updated Government Functional Standard GovS 002 version 2.1 was published in September 2025 | Public-sector projects and suppliers should consider governance, accountability and delivery expectations |
| Digital stakeholder engagement | Businesses increasingly have access to collaboration, feedback and AI-supported analysis tools | Greater opportunities for engagement monitoring, subject to human oversight and privacy safeguards |
These developments do not create identical responsibilities for every business.
For example, the UK Corporate Governance Code applies to specified categories of listed companies, not automatically to ordinary privately owned startups.
However, smaller companies dealing with larger corporate clients may encounter more demanding reporting and risk-management expectations through commercial agreements.
Similarly, stakeholder registers containing identifiable individuals’ information must be managed in accordance with applicable data protection law.
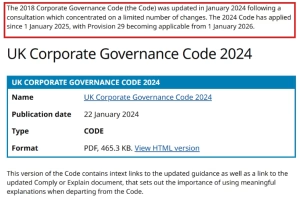
The Financial Reporting Council explains the UK Corporate Governance Code and the introduction of Provision 29 for financial years beginning on or after 1 January 2026.
Who Are the Main Stakeholders in a Business?
Stakeholders include individuals and organisations that influence a business or experience the consequences of its decisions.
They are usually divided into internal and external stakeholders, although some relationships can overlap.
Internal Stakeholders
Internal stakeholders are directly involved in the business’s operations, ownership or governance.
They may include founders, directors, shareholders, department managers, employees, project teams and internal advisers.
For startups, founders and employees often hold several responsibilities simultaneously.
This makes clearly defined decision-making authority particularly important.
A founder may be responsible for commercial strategy, investor communication and supplier negotiations. Without clear ownership, important issues can be overlooked.
As a business grows, responsibilities may need to be transferred to specialist managers or senior leaders.
For example, appointing a Chief Human Resources Officer may become relevant where workforce planning, organisational changes and employee engagement require greater strategic oversight.
External Stakeholders
External stakeholders operate outside the business but can influence or be affected by its activities.
| Stakeholder group | Main interests | Possible engagement approach |
| Investors | Financial performance, risks, growth | Financial updates and board discussions |
| Customers | Price, quality, reliability | Feedback surveys and customer interviews |
| Suppliers | Payment terms and purchasing forecasts | Procurement reviews |
| Banks and lenders | Repayment capacity and financial stability | Financial reporting |
| Regulators | Compliance and public protection | Formal submissions and required consultations |
| Local communities | Employment, environment, disruption | Community meetings and feedback channels |
| Business partners | Commercial returns and shared responsibilities | Partnership reviews |
| Professional advisers | Legal, financial and operational compliance | Specialist consultations |
Not every stakeholder needs the same amount of attention.
A potential investor may have significant influence over a fundraising decision, while an individual customer may have limited formal decision-making power.
However, low formal influence does not mean a stakeholder’s interests are unimportant.
Employees, vulnerable customers and communities directly affected by a project may require substantial engagement even when they cannot influence senior management decisions.
How Do You Create a Stakeholder Engagement Plan Step by Step?
We recommend developing stakeholder engagement through eight connected stages. Each stage should produce information that can be used in the next.
Step 1: Define Your Business Objectives
Begin by explaining why stakeholder engagement is necessary.
A plan without specific objectives often becomes a collection of meetings rather than a management tool.
For example, a startup launching a new product in 2027 could establish the following targets:
| Objective | Illustrative target | Deadline |
| Confirm supplier readiness | 100% of critical suppliers reviewed | Before launch |
| Obtain investor approval | All required approvals received | Before committing expenditure |
| Gather customer feedback | 50 completed interviews or surveys | Before product finalisation |
| Prepare employees | 90% training completion | Before launch |
| Resolve critical stakeholder concerns | 100% addressed or formally escalated | Before go-live |
These are suggested planning targets, not industry-wide performance statistics.
They should be adjusted to the size, financial resources and complexity of the project.
A company raising investment may need to place greater emphasis on financial reporting, shareholder expectations and investment milestones.
The process of attracting business investors also requires founders to demonstrate that operational commitments are achievable and management responsibilities are clearly allocated.
Step 2: Identify Every Relevant Stakeholder
Create a stakeholder register covering individuals, departments and external organisations.
A useful register should contain each stakeholder’s role, relationship to the project, interests, contact arrangements and involvement requirements.
Start with the following questions:
- Who will make or approve important decisions?
- Who provides essential funding, resources or services?
- Who will experience operational or financial changes?
- Who could delay, challenge or stop the project?
- Who possesses information the project team needs?
- Who may be disadvantaged if their concerns are ignored?
- Which stakeholders are not currently represented?
The last question is especially important.
Businesses sometimes identify people with formal authority but overlook those who are most directly affected.
For instance, warehouse employees may understand practical inventory problems better than senior managers who rarely use the systems being replaced.
At this stage, our preferred approach is to include potentially affected stakeholders before determining how much engagement each requires.
Step 3: Analyse Stakeholder Influence and Interest
Once the register has been prepared, assess each stakeholder’s influence over the project and their interest in its outcomes.
A power-interest matrix is one of the most practical tools for making this assessment.
| Stakeholder category | Power | Interest | Recommended approach |
| Manage closely | High | High | Direct involvement and frequent communication |
| Keep satisfied | High | Low | Targeted updates and consultation on important decisions |
| Keep informed | Low | High | Regular information and opportunities to provide feedback |
| Monitor | Low | Low | Appropriate updates and periodic reassessment |
For example, a major investor may have high power and high interest when a startup is seeking additional capital.
An external regulatory body may have substantial authority but limited day-to-day involvement.
Employees directly affected by a technology change may have high interest and lower formal decision-making authority.
The matrix helps allocate communication effort, but it must not be used to dismiss stakeholder rights, legal consultation duties or significant negative impacts.
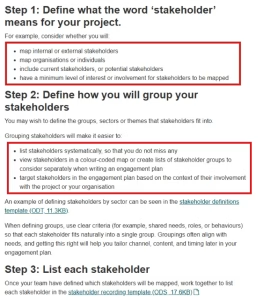
UK Government Analysis Function guidance explains how to define, group and identify stakeholders before developing an engagement strategy.
Step 4: Calculate Stakeholder Engagement Priority
A stakeholder scoring model can help startups compare competing engagement demands.
For example, we can use a weighted assessment containing four factors.
| Assessment factor | Suggested weighting |
| Operational or stakeholder impact | 40% |
| Decision-making influence | 30% |
| Importance to an upcoming milestone | 20% |
| Relationship or disagreement risk | 10% |
| Total | 100% |
Each factor is rated from 0 to 5.
The stakeholder priority percentage is then calculated by dividing each rating by five, multiplying it by its weighting and adding the four results.
Example calculation:
A critical supplier receives the following ratings:
- Impact: 5/5
- Influence: 4/5
- Milestone importance: 5/5
- Relationship risk: 4/5
Priority score = (5 ÷ 5 × 40) + (4 ÷ 5 × 30) + (5 ÷ 5 × 20) + (4 ÷ 5 × 10)
Final priority score: 92%
For comparison, a hypothetical startup might produce these results:
| Stakeholder | Illustrative priority score | Recommended engagement |
| Critical supplier | 92% | Weekly delivery and risk reviews |
| Product customers | 86% | Product testing and regular feedback |
| Lead investor | 80% | Financial and milestone reporting |
| Employees | 72% | Team briefings and consultation |
| Local community | 64% | Targeted engagement and feedback |
These percentages represent our illustrative prioritisation methodology. They are not measured stakeholder satisfaction levels or independently established industry benchmarks.
The weighting should change where the project involves public safety, statutory consultation, environmental impacts or other circumstances requiring special attention.
Step 5: Establish a Communication Strategy
Stakeholder engagement should be matched to the information people need and the decisions they can influence.
A communication plan should specify:
- What information must be provided.
- Why the information matters.
- Which channel will be used.
- How frequently engagement will occur.
- Who is responsible for the relationship.
- What feedback or approval is required.
- How unresolved concerns will be escalated.
| Stakeholder | Communication channel | Frequency | Relationship owner |
| Investors | Financial reports and meetings | Monthly or at agreed milestones | Founder or finance director |
| Employees | Team meetings and internal updates | Weekly | Department manager |
| Customers | Interviews, surveys and product updates | At defined product milestones | Product or customer experience lead |
| Suppliers | Delivery reviews and email | Weekly during critical phases | Operations manager |
| Regulators | Required reporting channels | As legally required | Compliance lead |
| Community groups | Consultation meetings and updates | According to project impact | Project or community lead |
We recommend avoiding unnecessary communications that provide no relevant information.
An investor may prefer a concise monthly financial report instead of frequent operational messages.
Employees working through a major system transition, however, may require daily guidance during the implementation period.
Clear internal communication is also central to maintaining productive workplace relationships. Startups can strengthen this process by establishing consistent communication practices before their teams become significantly larger.
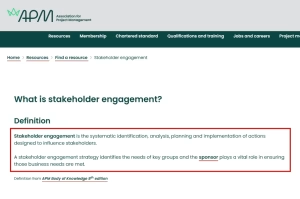
The Association for Project Management explains stakeholder engagement and the importance of identifying stakeholder interests and influence.
Step 6: Assign Accountability and Decision-Making Responsibilities
Every important stakeholder relationship should have a clearly identified owner.
Without accountability, businesses may repeatedly collect feedback without responding to it.
For larger projects, a responsibility assignment matrix can help explain who is:
- Responsible for carrying out engagement activities.
- Accountable for approving decisions.
- Consulted before decisions are finalised.
- Informed once decisions have been made.
This is commonly referred to as the RACI approach.
For example, the operations manager may be responsible for negotiating delivery schedules, while the founder is accountable for approving significant contractual changes.
The finance team may need to be consulted before new payment terms are accepted.
The company should document these responsibilities alongside its wider work breakdown structure so that stakeholder engagement activities are connected to project deliverables.
Step 7: Record Feedback and Manage Disagreements
An engagement plan should establish how the business will respond when stakeholders disagree.
Disagreement is not automatically evidence of poor engagement.
In some cases, it provides information that helps the company avoid costly decisions.
For example, a supplier might challenge a planned launch date because essential components cannot be delivered on time.
A productive response would involve reviewing the delivery evidence, assessing alternative options and documenting any revised commitment.
Our preferred approach is to maintain a feedback and issue log that records:
| Field | Information required |
| Stakeholder | Person or group raising the concern |
| Issue | Clear explanation of the problem |
| Business impact | Financial, operational or reputational consequences |
| Priority | Routine, significant or critical |
| Owner | Person responsible for resolution |
| Action | Proposed corrective measure |
| Deadline | Expected response or decision date |
| Status | Open, under review, resolved or escalated |
For high-risk disputes, the company should establish an escalation route to senior management or relevant advisers.
A concern that changes the agreed project scope, price or contractual obligations should follow appropriate change-control procedures rather than being treated as an informal promise.
Step 8: Review Engagement Performance and Update the Plan
The final stage involves monitoring whether engagement activities are delivering their intended outcomes.
A stakeholder register should not remain unchanged throughout a project.
Stakeholder influence, expectations and involvement can change as the business grows.
For instance, a supplier may become more influential when demand increases, or new investors may require different reporting arrangements after a funding round.
The plan should therefore be reviewed at meaningful intervals and whenever major commercial circumstances change.
We recommend a monthly review for many startup projects, with more frequent checks during high-risk implementation periods.
What Should a Stakeholder Engagement Plan Template Include?
A practical stakeholder engagement template should provide one central record that connects stakeholder analysis with planned actions.
The following example can be adapted for product launches, digital transformation, business expansion or investment projects.
Stakeholder Engagement Plan Template for 2027
| Planning field | Example entry |
| Project name | New software product launch |
| Business objective | Launch a customer-ready product |
| Project sponsor | Managing director |
| Engagement owner | Project manager |
| Main stakeholder groups | Investors, customers, staff, suppliers |
| Main engagement objective | Confirm readiness and address critical concerns |
| Engagement period | January–June 2027 |
| Communication methods | Meetings, reports, interviews and surveys |
| Review frequency | Monthly |
| Main performance indicators | Stakeholder coverage, feedback closure and approval completion |
| Escalation responsibility | Project sponsor |
| Final review | Post-launch evaluation |
The template should be supported by a working stakeholder register containing more detailed information.
| Stakeholder | Current position | Desired position | Required action | Owner |
| Lead investor | Supportive | Actively endorsing | Review commercial milestones | Founder |
| Product team | Supportive | Leading | Confirm delivery responsibilities | Product lead |
| Main supplier | Neutral | Supportive | Agree delivery commitments | Operations lead |
| Pilot customers | Unaware | Contributing | Arrange product feedback sessions | Customer lead |
| Employees | Neutral | Supportive | Training and consultation | People manager |
The current and desired positions are judgement-based assessments that should be updated using actual discussions and observable behaviour.
Importantly, a stakeholder does not always need to become an enthusiastic supporter.
For an external party whose main concern is that a project does not create unnecessary disruption, reaching a position of informed neutrality may be an entirely satisfactory outcome.
What Does a Stakeholder Engagement Plan Look Like in a Realistic Startup Scenario?
Consider a hypothetical UK technology startup preparing to launch a subscription-based business management platform in 2027.
The company has a total project budget of £120,000 and plans to launch its first commercial version within six months.
Its stakeholders include two investors, a small development team, a payment technology provider, trial customers and an outsourced customer support partner.
The business faces three main engagement risks.
First, investors need confidence that the launch budget and revenue assumptions are realistic.
Second, customers need sufficient opportunities to test the product before commercial release.
Third, external suppliers must confirm that critical services will be available when the product launches.
A stakeholder engagement plan could address these risks through the following activities.
| Project phase | Engagement activity | Expected outcome |
| January 2027 | Investor and team planning meetings | Agreed objectives and responsibilities |
| February 2027 | Customer discovery interviews | Validated user requirements |
| March 2027 | Supplier readiness reviews | Confirmed delivery dependencies |
| April 2027 | Product demonstrations and feedback | Prioritised product improvements |
| May 2027 | Final investor and operational review | Approval to proceed |
| June 2027 | Launch communications and evaluation | Measured stakeholder feedback |
This approach also supports stronger market research because potential customers become active participants in testing the product rather than receiving information only after launch.
The underlying engagement evidence can subsequently strengthen financial forecasts, operational plans and investor presentations.
How Much Should a Startup Budget for Stakeholder Engagement?
Stakeholder engagement requires resources, although not every business needs specialist software or external consultants.
For the hypothetical £120,000 project, the company might allocate £5,000 towards engagement activities.
| Engagement expense | Illustrative budget |
| Internal coordination and management time | £2,000 |
| Customer interviews and analysis | £1,000 |
| Customer research incentives | £400 |
| Stakeholder workshops | £750 |
| Accessible communication materials | £350 |
| Contingency | £500 |
| Total | £5,000 |
This represents approximately 4.17% of the overall project budget.
The percentage is an example, not a recommended universal allocation.
A straightforward internal project could require considerably less. A project involving extensive public consultation, sensitive workforce changes or major environmental impacts could require significantly more.
The correct budget depends on the number of affected stakeholders, the project duration, complexity, legal requirements and potential consequences of disengagement.
Startups applying for business funding should include material stakeholder engagement costs in their wider financial forecasts rather than treating them as unplanned expenditure.
How Can Businesses Measure Stakeholder Engagement Effectiveness?
Stakeholder engagement is difficult to improve when performance is assessed only through informal opinions.
Our recommended approach is to combine quantitative indicators with qualitative feedback.
Quantitative indicators can establish whether planned activities were completed.
Qualitative feedback helps explain whether the engagement was meaningful.
Stakeholder Engagement KPIs for 2027
| KPI | Example target | Measurement |
| Priority stakeholder coverage | 95% | Priority stakeholders contacted ÷ total priority stakeholders |
| Planned engagement completion | 90% | Completed engagements ÷ planned engagements |
| Feedback closure rate | 85% | Resolved feedback items ÷ feedback items due for resolution |
| Milestone approval completion | 100% | Required approvals secured before deadline |
| Employee participation | 80% | Participating employees ÷ eligible employees |
| Stakeholder satisfaction | 80% | Average satisfaction score converted to a percentage |
| Critical issue response | 100% | Critical issues acknowledged within agreed response period |
These values are illustrative management targets. They should not be presented as national averages or guaranteed performance standards.
For example, a company seeking a 90% engagement completion rate that successfully carries out 36 of 40 planned activities achieves:
36 ÷ 40 × 100 = 90%
However, this does not establish that 90% of stakeholders support the project.
Completion, sentiment and outcome measures answer different questions and should be tracked separately.
What Is a Good Stakeholder Engagement Score?
There is no single percentage that defines successful stakeholder engagement across all industries.
Our proposed internal assessment framework gives four areas equal weighting.
| Assessment area | Weight |
| Engagement activity completion | 25% |
| Stakeholder satisfaction | 25% |
| Feedback resolution | 25% |
| Required decision and approval completion | 25% |
A business can calculate a combined management score using the weighted results.
For example, activity completion of 90%, satisfaction of 80%, feedback resolution of 85% and approval completion of 100% would produce an overall illustrative score of 88.75%.
This is a convenient internal monitoring figure rather than a formally validated stakeholder engagement index.
A strong result in one category should not obscure a critical failure in another. A company cannot compensate for a missing legal approval simply by holding more meetings.
We therefore recommend reporting individual indicators alongside any overall score.
How Should Stakeholder Engagement Strategies Differ by Industry?
An effective stakeholder engagement strategy should reflect the commercial and operational characteristics of the business.
Technology Startups and SaaS Businesses
Technology companies frequently depend on customer adoption, software reliability, security and third-party integrations.
Their engagement strategies should concentrate on user feedback, product development priorities, service providers and investor expectations.
Product teams should distinguish between requests that improve the product’s wider commercial value and individual preferences that would create excessive development costs.
Customer feedback should inform prioritisation, but it should not automatically determine every product decision.
Retail and E-commerce Startups
Retail businesses depend heavily on suppliers, logistics providers, employees and customers.
Late deliveries, poor supplier communication and inconsistent product availability can affect revenue and customer confidence.
Engagement plans should therefore establish clear purchasing forecasts, delivery arrangements, escalation procedures and customer communication responsibilities.
Professional Services Businesses
Consultancies, agencies, accountancy practices and other professional service providers rely on client trust and clearly defined service expectations.
Their engagement plans should cover project scope, approval responsibilities, reporting frequency and how changes will be managed.
Contractual misunderstandings can become particularly costly when clients request additional services outside the original agreement.
A structured engagement plan can help identify these changes early and ensure that the relevant commercial arrangements are reviewed.
Construction and Property Businesses
Construction projects often require engagement with contractors, clients, planning authorities, neighbouring communities and other affected parties.
Issues may involve access, noise, environmental impacts, procurement, safety and delivery schedules.
Projects with significant community consequences should establish genuine opportunities for affected people to raise concerns, not merely issue progress announcements.
Legal consultation and notification requirements must be considered separately from voluntary stakeholder engagement.
Healthcare and Regulated Businesses
Healthcare-related startups and companies operating in regulated industries may face more demanding expectations concerning confidentiality, professional responsibilities, safety and operational oversight.
Relevant regulators, customers, employees and professional advisers should be involved at the appropriate stages.
The engagement plan should distinguish between commercial preferences and mandatory compliance requirements.
How Can Startups Manage Resistant or Disengaged Stakeholders?
Resistance is one of the most challenging aspects of stakeholder engagement.
An employee may fear losing responsibilities after a technology change. A supplier may disagree with new payment terms, while an investor may question whether projected revenue justifies the proposed expenditure.
The first step is to establish the underlying reason for the concern.
Businesses should avoid assuming that resistance reflects an unwillingness to cooperate.
Judith Donaldson, writing for the Association for Project Management about organisational change, explains that “the focus of change management is to prepare your business for disruption”.
This distinction matters because communication alone may not resolve the operational consequences of a proposed change.
For example, explaining a new software system to employees will not resolve their concerns if they have not received sufficient training.
Similarly, sending financial reports to investors may not resolve disagreements about spending priorities.
Effective engagement may require revised timelines, additional evidence, negotiated commercial arrangements or changes to project design.
| Stakeholder concern | Possible underlying issue | Appropriate response |
| Employees resist new technology | Training or job-security concerns | Consultation, practical training and clear explanations |
| Investor challenges spending | Weak financial assumptions | Revised forecasts and sensitivity analysis |
| Supplier rejects delivery timetable | Capacity constraints | Review milestones and alternatives |
| Customers reject product changes | Reduced usefulness or increased cost | User research and product reassessment |
| Local community opposes a project | Disruption or insufficient consultation | Meaningful dialogue and mitigation measures |
Businesses should document disagreements, the evidence considered and the final decisions.
Not every request can be accepted, but stakeholders should understand how their input was assessed.
How Should Stakeholder Data and AI Tools Be Managed in 2027?
Digital platforms can make stakeholder engagement more organised.
Customer relationship management systems, project management applications and survey tools can support contact management, reporting and feedback analysis.
AI-supported tools may also help organise meeting notes, identify recurring concerns and summarise large volumes of stakeholder feedback.
However, the use of technology should not reduce transparency or accountability.
Where stakeholder records contain personal information, businesses need an appropriate lawful basis for processing, clear privacy information and suitable security arrangements.
The Information Commissioner’s Office updated guidance in October 2026 following changes under the Data (Use and Access) Act.
Companies preparing engagement plans for 2027 should review their processes for collecting, retaining, sharing and deleting personal contact information.
Sensitive relationship assessments, such as an individual’s perceived willingness to support a project, should not be circulated unnecessarily.
Businesses should also avoid uploading confidential investor information, employee records or personal stakeholder details into AI services without first assessing the relevant confidentiality, security and data protection risks.
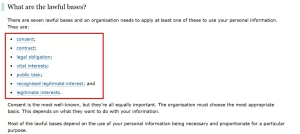
ICO guidance explains the lawful bases for processing personal information and the importance of informing individuals how their data is used.
What Are the Most Common Stakeholder Engagement Planning Mistakes?
Our assessment identifies several recurring weaknesses in the design of stakeholder engagement plans.
| Planning mistake | Potential consequence | Recommended improvement |
| Identifying only powerful stakeholders | Affected groups may be overlooked | Assess impact and vulnerability as well as power |
| Using identical communication for everyone | Irrelevant information and disengagement | Tailor messages and channels |
| Failing to allocate ownership | Delayed decisions and unresolved concerns | Assign one responsible relationship owner |
| Measuring only meeting attendance | Limited evidence of meaningful engagement | Include feedback and outcome measures |
| Ignoring engagement costs | Budget overruns | Forecast time and resources |
| Creating an overly complex register | Low adoption by smaller teams | Begin with essential fields |
| Failing to review stakeholder positions | Outdated assumptions | Reassess at project milestones |
| Promising outcomes without approval | Commercial or contractual disputes | Apply formal decision and change controls |
The most significant mistake is confusing communication volume with engagement quality.
A company that sends weekly newsletters but never responds to stakeholder concerns may have an active communication programme without achieving meaningful engagement.
In contrast, a business that holds fewer but well-structured consultations and implements appropriate improvements may achieve better results.
How Often Should a Stakeholder Engagement Plan Be Reviewed?
There is no single review schedule suitable for every organisation.
We recommend setting review dates according to project complexity, risk exposure and stakeholder needs.
| Business situation | Suggested review frequency |
| Small startup with stable operations | Monthly |
| Major product launch | Fortnightly or at key milestones |
| High-risk system implementation | Weekly during critical phases |
| Investor-funded expansion | Monthly, alongside financial reporting |
| Significant organisational restructuring | Weekly or as circumstances require |
| Long-term strategic partnerships | Quarterly, with additional milestone reviews |
These are practical suggestions rather than statutory requirements.
A full reassessment should also be considered after a major ownership change, funding event, operational incident, important contractual change or substantial alteration to the project’s scope.
For founders planning wider expansion, stakeholder reviews should form part of the organisation’s general business development and financial planning cycle.
What Should a 90-Day Stakeholder Engagement Action Plan Include?
Businesses beginning a new engagement programme can use a 90-day implementation schedule rather than attempting to establish every process immediately.
| Period | Main activity | Expected deliverable |
| Days 1–15 | Identify stakeholders and clarify objectives | Initial stakeholder register |
| Days 16–30 | Assess impact, influence and priorities | Stakeholder map and priority scores |
| Days 31–45 | Assign owners and design communication activities | Engagement schedule |
| Days 46–60 | Conduct meetings, interviews and consultations | Feedback and issue log |
| Days 61–75 | Address concerns and review initial outcomes | Corrective action plan |
| Days 76–90 | Measure KPIs and revise the approach | Updated stakeholder engagement plan |
For startups, the first 30 days should concentrate on identifying the relationships most likely to affect important financial or operational decisions.
The next 30 days should establish meaningful communication and consultation procedures.
The final 30 days should demonstrate whether the engagement activities have led to better decisions, clearer responsibilities or resolved concerns.
This process creates a practical foundation for longer-term relationship management without requiring a complex corporate structure.
Conclusion
A successful stakeholder engagement plan for 2027 should help UK businesses make better decisions, manage financial and operational risks, and maintain productive relationships with the people affected by their activities.
Our analysis suggests that the strongest plans combine stakeholder mapping, clear ownership, realistic budgets, meaningful consultation and measurable performance indicators.
Startups do not need complicated systems to achieve these objectives. A well-maintained register, structured communication schedule and consistent feedback process can provide an effective starting point.
The important principle is to treat stakeholder engagement as an ongoing business responsibility, with evidence of how stakeholder input influences decisions and contributes to sustainable growth.
Frequently Asked Questions About Stakeholder Engagement Plans
What are the five key elements of a stakeholder engagement plan?
The five main elements are stakeholder identification, stakeholder analysis, engagement objectives, communication and participation activities, and performance monitoring. Strong plans also define relationship ownership, timelines and escalation procedures.
What is the difference between a stakeholder engagement plan and a communication plan?
A communication plan primarily explains how information will be shared. A stakeholder engagement plan goes further by establishing how stakeholders will be consulted, involved in decisions and supported throughout a project.
Can a small business create a stakeholder engagement plan?
Yes. Small businesses can use a simple spreadsheet containing stakeholder names, interests, priorities, communication methods, relationship owners and review dates. Specialist software is not always necessary.
How do you measure stakeholder engagement success?
Useful measures include stakeholder satisfaction, engagement completion, feedback resolution, participation, approval completion and project outcomes. Each metric should have a clearly defined calculation and target.
Who is responsible for creating a stakeholder engagement plan?
A project manager, founder, business owner or designated engagement lead will usually prepare the plan. Senior management should approve important objectives and ensure that responsibilities and resources are clearly allocated.
Is a stakeholder engagement plan legally required in the UK?
There is no general requirement for every UK business to maintain one. However, specific projects and sectors may have consultation, notification, governance, reporting or other legal obligations that must be satisfied.
What is the difference between stakeholder mapping and stakeholder engagement?
Stakeholder mapping identifies and evaluates the individuals or groups connected to a project. Stakeholder engagement involves communicating, consulting, collaborating and responding to those stakeholders over time.
Blogger & Content creator | An insightful writer sharing practical advice for UK entrepreneurs
Related Articles in Business
View All →
Starting a Business in London: How to Identify Market Trends and Emerging Opportunities
London remains one of the UK’s most attractive destinations for entrepreneurs, offering access to international markets, skilled professionals, diverse communities and a thriving business ecosystem. However, starting a…
Is Wetherspoons a Franchise? Costs, Ownership, Requirements and How to Apply in 2026
Yes, Wetherspoons is a franchise. J D Wetherspoon, one of Britain’s largest pub operators, now offers franchise opportunities to eligible hospitality businesses, experienced operators, investors and organisations. However,…
Amazon Delivery Franchise Cost UK: Investment, Profit, Fees and Requirements
The Amazon delivery franchise cost in the UK starts from approximately £10,000, while prospective business owners are generally expected to demonstrate at least £25,000 in liquid assets. This…