Statement of Profit and Loss: Meaning, Format and Example for UK Businesses

UK Startup Blog Archive
Table of Contents
A statement of profit and loss shows how much money a business earned, what it spent and whether it ultimately made a profit or loss during a particular period.
Also known as a profit and loss statement, P&L or income statement, it is one of the most useful financial reports for understanding business performance.
Rather than simply checking how much money is sitting in your bank account, a P&L allows you to see where revenue is coming from, how much it costs to generate that revenue and whether operating expenses are becoming difficult to control.
For UK startups and small businesses, regularly reviewing a profit and loss statement can support pricing, budgeting, funding decisions, tax preparation and longer-term financial planning.
What Does a Statement of Profit and Loss Tell You About a Business?
A statement of profit and loss tells you whether the activities of a business generated a profit or produced a loss during a specific accounting period.
It begins with income generated by the business and gradually deducts the costs associated with earning that income. What remains at the bottom of the statement is normally the net profit or net loss.
This means a P&L can answer important questions such as whether sales are growing, whether costs are increasing faster than revenue and whether the underlying business model is becoming more or less profitable.
For example, a startup could increase annual sales from £100,000 to £140,000 and initially appear to be performing well. However, if its costs increase from £80,000 to £125,000 during the same period, profit growth is much less impressive.
Looking only at sales would therefore give an incomplete picture.
Why Is a Profit and Loss Statement Important for UK Businesses?
A P&L gives business owners a structured way to monitor financial performance rather than relying on bank balances or sales figures alone.
It can help you understand whether prices are high enough to cover costs, where spending is increasing and whether business growth is actually translating into additional profit.
Regular P&L reviews can also support:
- Pricing Decisions: Check whether products and services generate enough margin after direct costs
- Cost Control: Identify expenses that are rising disproportionately
- Business Planning: Compare actual financial performance with expected results
- Funding Applications: Provide lenders or investors with evidence of historical trading performance
A strong P&L becomes particularly useful when used alongside a realistic business plan, cash-flow forecasts and a balance sheet.
What Information Is Included in a Profit and Loss Statement?
The exact layout depends on the size and nature of the business, but most statements follow a similar sequence from revenue through to final profit.
Revenue
Revenue is the income generated through the normal activities of the business before expenses are deducted.
For a retailer, this could be product sales. A consultancy may record professional fees, while a software company could generate subscription revenue.
Revenue is sometimes referred to as sales or turnover.
Cost of Sales
Cost of sales includes costs directly connected with producing the goods or delivering the services being sold.
Examples could include raw materials, stock purchases, manufacturing costs or certain direct labour costs.
The important distinction is that these costs are closely connected to generating the relevant sale.
Gross Profit
Gross profit shows how much remains after direct costs have been deducted from revenue.
The basic calculation is:
Gross Profit = Revenue − Cost of Sales
If a business earns £100,000 in revenue and incurs £40,000 of direct costs, its gross profit is £60,000.
Operating Expenses
Operating expenses are the general costs of running the business that are not directly attributable to producing each individual sale.
These could include rent, office costs, salaries, insurance, accounting fees, software, advertising and administration.
Accurate categorisation is important, which is why maintaining reliable bookkeeping for small businesses throughout the year makes preparing a P&L much easier.
Operating Profit
Operating profit shows the profit generated by normal business operations after operating expenses have been deducted from gross profit.
It can be particularly useful because it helps you understand how the core business performs before certain financing and tax costs are considered.
Interest and Other Income or Expenses
Businesses may have financial items that do not arise directly from their normal trading activities.
These might include interest received, interest paid on borrowing or other non-operating items.
Tax
For a limited company, Corporation Tax is calculated separately based on taxable profits rather than simply taking the accounting profit shown in the P&L and multiplying it by a tax rate.
Accounting adjustments and tax rules can cause taxable profit to differ from accounting profit.
Net Profit or Loss
Net profit is usually the final figure after the relevant expenses, finance costs and tax have been taken into account.
A positive result means the business has made a profit for the period. A negative figure represents a loss.
How Do You Prepare a Statement of Profit and Loss?
Start by deciding which period the statement should cover. Businesses commonly prepare monthly, quarterly and annual P&Ls depending on how closely they want to monitor performance.
Then gather accurate financial records for the period, including sales, invoices, purchases, payroll and operating expenses.
A straightforward process is:
- Record total revenue for the period
- Calculate cost of sales
- Subtract cost of sales to determine gross profit
- Record operating expenses
- Calculate operating profit
- Include relevant finance and other items
- Account for applicable tax
- Calculate the final profit or loss
Accounting software can automate much of this process when transactions have been recorded and categorised correctly.
However, automation does not remove the need to review the figures. Incorrect transaction categories can still produce a misleading P&L.
What Is the Difference Between Cash and Accrual Accounting in a Profit and Loss Statement?
The accounting method used can affect when income and expenses appear.
Under cash accounting, transactions are generally recognised when money is actually received or paid. Under accrual accounting, income and expenses are recognised when they are earned or incurred, even if payment takes place later.
Suppose a business issues a £5,000 customer invoice on 20 December but does not receive payment until January.
Under accrual accounting, the £5,000 may form part of December’s revenue because that is when the income was earned. A cash-based approach would generally recognise it when the payment arrives.
This distinction is particularly important when comparing profit with cash in the bank.
Limited companies preparing statutory accounts need to follow applicable accounting standards, so business owners should not assume that a bank transaction report is automatically the same as a formal profit and loss account.
What Is the Difference Between a Profit and Loss Statement, Balance Sheet and Cash Flow Statement?
These reports measure different aspects of financial health.
| Financial Statement | What It Shows | Key Question |
| Profit and Loss Statement | Revenue, costs and profit over a period | Is the business profitable? |
| Balance Sheet | Assets, liabilities and equity at a particular date | What does the business own and owe? |
| Cash Flow Statement | Movement of cash into and out of the business | Where is cash coming from and going? |
A P&L could show a profitable business while its bank account is under pressure because customers have not yet paid their invoices.
For that reason, none of these statements should be viewed completely in isolation.
How Do You Read and Analyse a Profit and Loss Statement?
Start at the top with revenue and work down rather than jumping immediately to net profit.
Compare revenue with previous periods and determine whether sales are growing. Next, examine how much of that revenue remains after direct costs.
Then assess operating expenses to see whether overheads are increasing faster than the business.
Several ratios can make comparisons easier.
Gross Profit Margin
Gross profit margin measures the proportion of revenue remaining after cost of sales.
Gross Profit Margin = Gross Profit ÷ Revenue × 100
If revenue is £100,000 and gross profit is £60,000, the gross margin is 60%.
Operating Profit Margin
Operating profit margin measures how much profit the core business generates after operating expenses.
Operating Profit Margin = Operating Profit ÷ Revenue × 100
Tracking this percentage over time can show whether the business is becoming more efficient.
Net Profit Margin
Net profit margin measures how much final profit remains from each pound of revenue.
Net Profit Margin = Net Profit ÷ Revenue × 100
A declining net margin does not automatically mean a business is failing, particularly if it is deliberately investing in growth. However, the reason for the decline should be understood.
Vertical Analysis
Vertical analysis expresses individual P&L items as a percentage of revenue.
For example, if cost of sales rises from 35% of revenue to 48%, you can investigate whether supplier costs, discounts, pricing or production efficiency have changed.
Horizontal Analysis
Horizontal analysis compares results between different periods.
If revenue increased from £100,000 to £120,000, that represents 20% growth. You could then compare the change in expenses and profit over the same period.
The method helps identify trends that might not be obvious from a single year’s figures.
What Warning Signs Should You Look for in a Profit and Loss Statement?
One weak month does not necessarily signal a serious problem. What matters more is whether negative patterns continue.
A business should investigate when revenue is rising but profit is consistently falling. This can mean direct costs or overheads are increasing faster than sales.
A shrinking gross margin may indicate higher supplier costs, excessive discounting or weak pricing. Rapid growth in administrative expenses can also reduce the benefit of increased sales.
Another warning sign is when profits depend heavily on unusual or one-off income rather than normal trading activity.
Comparing several months or years usually provides a more useful picture than evaluating one period on its own.
Can a Profitable Business Still Have Cash Flow Problems?
Yes. Profit and cash are not the same thing.
Imagine a business records £70,000 of sales and £50,000 of expenses, producing an accounting profit of £20,000. However, £30,000 of those sales remain unpaid by customers.
The P&L may therefore show a profit while the business does not yet have enough available cash to comfortably pay wages, suppliers or tax.
This is one reason businesses seeking money to start or grow a business often need both profit projections and cash-flow forecasts.
A profitable company can still experience financial difficulty when customers pay slowly, stock absorbs large amounts of cash or significant bills become due before income is received.
What Is the Difference Between a Management P&L and a Statutory Profit and Loss Account?
A management P&L is primarily designed to help the owners and managers of a business make decisions.
It might be produced every month and contain detailed categories such as revenue by department, advertising expenditure, staff costs and individual product margins.
A statutory profit and loss account forms part of formal annual financial reporting and must follow applicable legal and accounting requirements.
The two reports may therefore be based on the same underlying financial records but serve different purposes.
A startup might use its monthly management P&L to decide whether advertising spending should increase, while the annual statutory accounts are prepared to meet reporting obligations.
What Is the Difference Between a P&L, Budget and Profit Forecast?
A P&L normally shows what has actually happened. A budget shows what the business intended to happen, while a forecast estimates what is now expected to happen.
Suppose a company originally budgeted for £250,000 of annual revenue.
After six months, the P&L shows actual revenue of £100,000 rather than the £125,000 expected by that point. Management might then revise its full-year forecast to £220,000.
Comparing these three figures can be valuable:
| Figure | Purpose |
| Actual P&L | Shows real financial performance |
| Budget | Shows the original financial target |
| Forecast | Shows the latest expected outcome |
The comparison helps business owners respond early instead of discovering a significant shortfall at the end of the year.
What Do Investors and Lenders Look for in a Profit and Loss Statement?
Investors and lenders rarely focus on one number alone.
Revenue growth can be attractive, but they may also consider whether gross margins are stable, whether operating costs are controlled and whether losses are narrowing or increasing.
For a startup, an investor may accept short-term losses when the business is deliberately spending on growth. However, they will normally want to understand how that expenditure could eventually translate into sustainable revenue and profit.
Lenders may place greater emphasis on whether operating performance appears strong enough to support repayments.
Consistency between the P&L, cash-flow forecast and business plan is also important. Large differences between documents may require explanation.
How Does a Profit and Loss Statement Affect Corporation Tax?
A limited company’s P&L provides an important starting point for determining its taxable profit, but accounting profit and taxable profit are not necessarily identical.
UK tax rules may require adjustments to accounting figures. Some costs recognised in the accounts may not receive the same treatment for Corporation Tax, while capital allowances and other tax adjustments can also affect the final calculation.
This means the net profit at the bottom of a P&L should not automatically be treated as the company’s taxable profit.
Businesses should calculate their tax position separately and make sure payments are made using the correct details and deadlines. The process for paying Corporation Tax is therefore separate from simply preparing the P&L.
Where transactions or tax adjustments are complex, professional accounting or tax advice may be appropriate.
Do UK Limited Companies Have to Prepare a Profit and Loss Account?
Yes. A UK limited company’s statutory annual accounts are prepared from its financial records and generally include a balance sheet, profit and loss account and notes to the accounts.
A director’s report is also generally required unless an applicable exemption applies, such as for qualifying micro-entities.
The profit and loss account shows the company’s sales, running costs and profit or loss over the financial year.
Preparing a profit and loss account does not necessarily mean that every company must currently publish the full document on the public Companies House register. Smaller companies may qualify for reduced filing requirements.
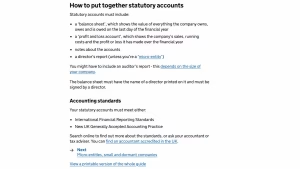
GOV.UK confirms that statutory accounts include a profit and loss account showing sales, running costs and the profit or loss made during the financial year.
Do Small Companies and Micro-Entities Have to File a Profit and Loss Account at Companies House?
The rules depend on company size and the filing options available.
For accounting periods beginning on or after 6 April 2025, a company can generally qualify as small when it meets at least two of these conditions: turnover of £15 million or less, a balance sheet total of £7.5 million or less and 50 employees or fewer.
A micro-entity generally needs to satisfy at least two of these thresholds: turnover of £1 million or less, a balance sheet total of £500,000 or less and 10 employees or fewer.
Qualifying small companies can currently choose not to send their profit and loss account to Companies House, while micro-entities can use simplified reporting arrangements. They must still prepare the accounts required for members and HMRC.
An important change was announced on 23 October 2026. The government paused the planned requirement for small companies and micro-entities to file profit and loss accounts with Companies House from April 2028.
Companies House confirmed that smaller businesses will continue to have options that allow profit and loss information to be removed from accounts placed on the public register while alternative filing arrangements are considered.
The separate move to mandatory commercial software filing remains scheduled for 1 April 2028.
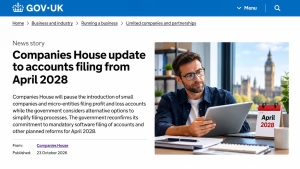
Companies House confirmed on 23 October 2026 that mandatory P&L filing for small companies and micro-entities from April 2028 has been paused.
What Records Do You Need to Prepare an Accurate Profit and Loss Statement?
A reliable P&L depends on accurate underlying records.
Businesses should keep evidence of income received or earned and expenses incurred, together with enough supporting information to explain each transaction.
Important records can include sales invoices, supplier invoices, receipts, payroll records, bank transactions, stock records and relevant tax records.
Keeping business and personal spending separate can also make financial reporting considerably easier. Limited companies should treat company money separately because the company is a distinct legal entity.
Regular reconciliation throughout the year is generally much easier than attempting to reconstruct transactions immediately before accounts are due.
What Does a Profit and Loss Statement Example Look Like for a UK Business?
Consider a small UK business comparing two financial years:
| Profit and Loss Item | 2025 | 2026 |
| Revenue | £100,000 | £135,000 |
| Cost of Sales | £40,000 | £52,000 |
| Gross Profit | £60,000 | £83,000 |
| Operating Expenses | £42,000 | £55,000 |
| Operating Profit | £18,000 | £28,000 |
| Interest and Other Costs | £2,000 | £3,000 |
| Profit Before Tax | £16,000 | £25,000 |
Revenue increased by 35%, while gross profit increased from £60,000 to £83,000.
Operating expenses also rose, but operating profit increased from £18,000 to £28,000. This suggests the additional revenue was strong enough to absorb higher overheads while still improving operating profitability.
However, this example would still need to be considered alongside the company’s cash position, balance sheet, tax position and any unusual transactions.
How Often Should a Business Prepare and Review a Profit and Loss Statement?
An annual P&L is useful for statutory reporting, but waiting until the end of the year provides limited value for day-to-day management.
Many small businesses benefit from reviewing a P&L monthly. This makes it easier to identify changes in sales, gross margin and operating costs before problems become significant.
Businesses with relatively simple or predictable activity may choose quarterly management reviews instead.
The appropriate frequency depends on the size, complexity and financial position of the business.
A rapidly growing startup with staff, marketing expenditure and substantial monthly transactions may need more frequent monitoring than a small business with relatively stable income and expenses.
Conclusion
A statement of profit and loss gives UK business owners a clear view of revenue, costs and profitability over a particular period.
Its real value goes beyond showing whether the final number is positive or negative.
By examining gross margin, operating costs and changes between periods, you can identify where the business is improving and where financial pressure may be developing.
For UK limited companies, the P&L also forms an important part of annual financial reporting, although what smaller businesses currently need to place on the public Companies House register depends on their eligibility and filing options.
Use your P&L alongside cash-flow information, your balance sheet, budgets and forecasts rather than relying on it alone. Together, these reports provide a much clearer picture of the financial health of the business.
FAQs
Is a Statement of Profit and Loss the Same as an Income Statement?
Yes. Profit and loss statement, P&L and income statement are commonly used to describe the financial statement showing revenue, expenses and profit or loss over a period.
Is a Profit and Loss Statement the Same as a P&L?
Yes. P&L is simply the abbreviation for profit and loss. Both terms refer to the same type of financial statement.
Does a Sole Trader Need a Profit and Loss Statement?
A sole trader needs accurate income and expense records to calculate business profit for tax purposes. Preparing a P&L can also make it much easier to monitor business performance.
Does a Limited Company Need a Profit and Loss Statement?
Yes. A profit and loss account forms part of a limited company’s statutory accounts, although qualifying small companies and micro-entities may currently have reduced Companies House filing requirements.
What Is the Difference Between Gross Profit and Net Profit?
Gross profit is revenue minus direct cost of sales. Net profit is what remains after the wider expenses and applicable financial items of the business have also been taken into account.
Can a Business Make a Profit but Still Have No Cash?
Yes. A business can show accounting profit while experiencing a cash shortage if customers have not paid, money is tied up in stock or large payments are due.
How Often Should You Review a Profit and Loss Statement?
Monthly reviews work well for many startups and small businesses because they make trends easier to identify. Businesses with simpler finances may find quarterly reviews sufficient.
Blogger & Content creator | An insightful writer sharing practical advice for UK entrepreneurs
Related Articles in Finance
View All →
If I Take Home £1,600 a Month, What Is My Salary in the UK?
If an employee takes home £1,600 per month in the UK, their estimated gross salary is approximately £21,780 per year. This is equal to about £1,815 per month…
Why the Two Year Accounts Rule is Not Actually a Rule?
Ask most new business owners when they can first apply for a mortgage and the answer comes back the same way every time: two years of accounts, minimum,…

Snap-on Franchise Cost: Fees, Investment and Earnings
The Snap-on franchise cost in the UK is currently quoted at £166,597 to £168,487 for the franchise investment, with Snap-on stating that a new franchisee may need to…