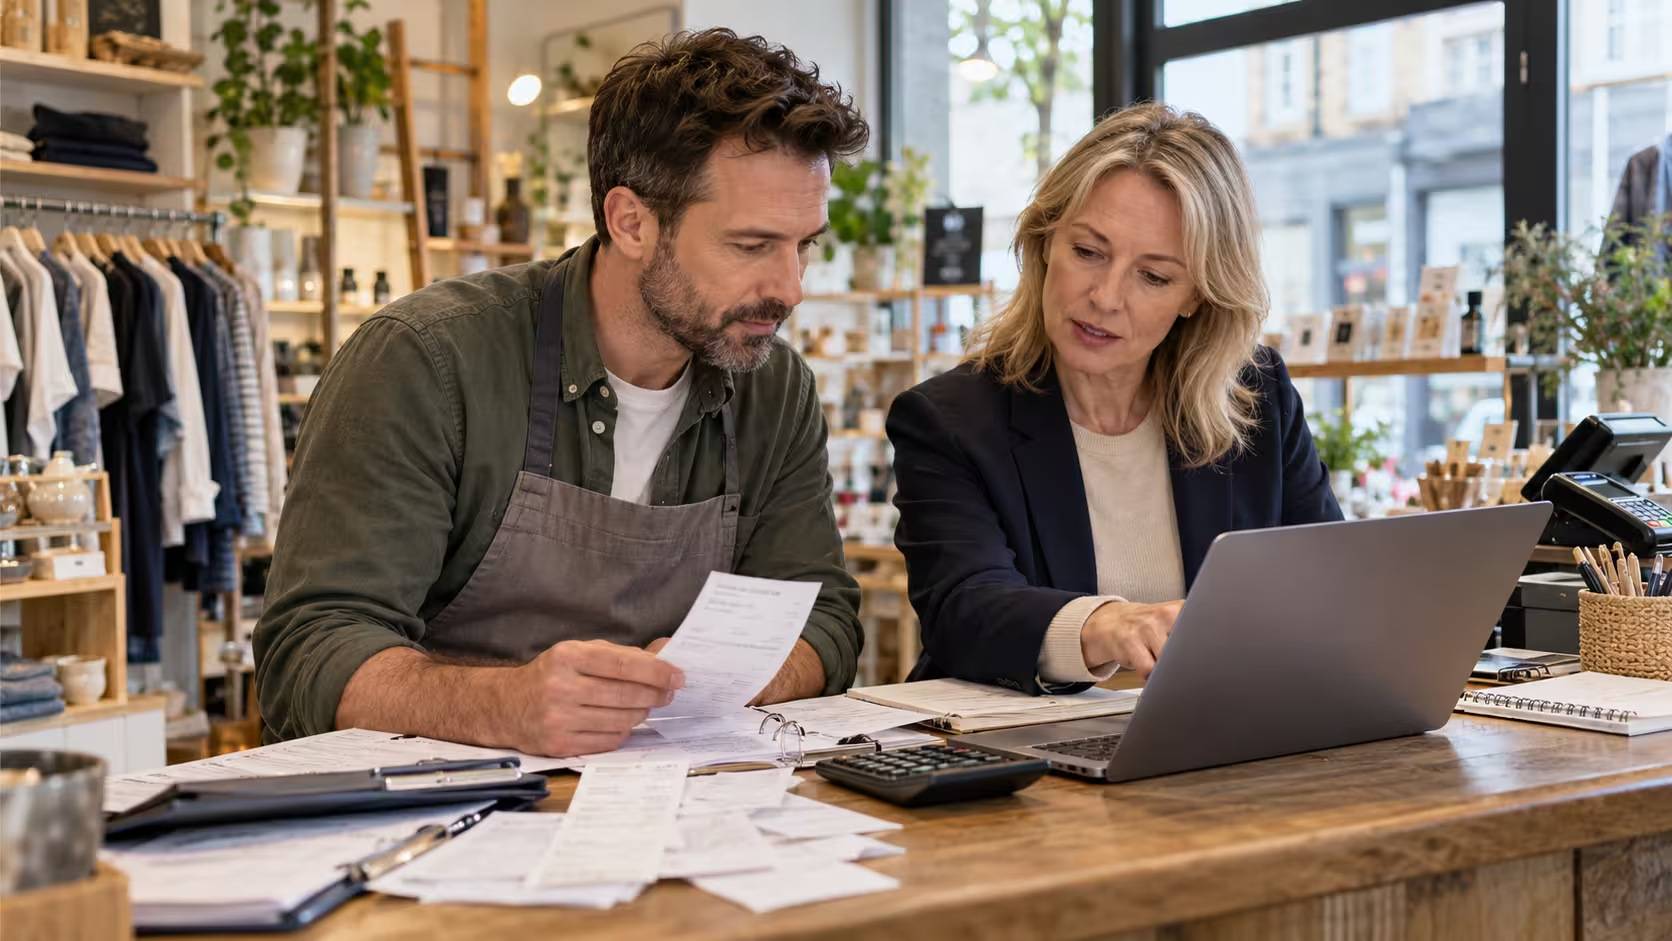
Bookkeeping Help for Small Business: Digital Records and Essential Tools

UK Startup Blog Archive
Table of Contents
Bookkeeping remains one of the foundations of running a small business, but the way businesses manage their books has changed considerably.
Paper ledgers, boxes of receipts and manual spreadsheets are increasingly being replaced by cloud accounting software, bank feeds, automated receipt capture and digital tax reporting.
For small businesses, bookkeeping is no longer simply about recording what has been spent and earned.
Accurate records can help owners understand cash flow, prepare for tax, monitor unpaid invoices, control costs and make better financial decisions.
The changes taking effect in 2026 also make digital record keeping more important for some sole traders and landlords.
Businesses therefore need to understand not only how bookkeeping works, but also when professional bookkeeping help for small business may be worthwhile.
Is Bookkeeping Still Used By Businesses In 2026?
Yes. Businesses are not abandoning bookkeeping. What they are moving away from is the older, highly manual way of doing it.
Every business still needs reliable information showing money coming in, money going out, amounts owed, expenses, sales and other financial transactions.
The technology used to collect and organise that information may have changed, but the underlying bookkeeping function remains necessary.
A modern small business may no longer maintain a handwritten cashbook. Instead, transactions might enter accounting software automatically through a bank feed.
Receipts may be photographed on a phone and attached to transactions, while invoices can be generated and monitored within the same system.
This means bookkeeping has evolved rather than disappeared.
Modern bookkeeping can help a business understand:
- Income: Money received from customers and other business sources
- Expenses: Costs incurred while operating the business
- Cash Flow: How much cash is entering and leaving the business
- Outstanding Invoices: Money customers have not yet paid
- Supplier Payments: Amounts owed to businesses and contractors
- Tax Position: Financial information needed to prepare tax returns
- Profitability: Whether income is covering costs and producing a profit
Businesses may perform these tasks internally, use software to automate part of the process or employ an external bookkeeper.
The method has changed, but maintaining accurate financial records remains essential.
How Has Bookkeeping Changed With Digital Accounting And Automation?
Traditional bookkeeping relied heavily on manual data entry. Someone would enter transactions individually, reconcile bank statements by hand and store supporting paperwork physically.
Cloud accounting platforms have changed much of this process.
Many modern systems can connect directly to business bank accounts and import transactions automatically.
Receipt-capture technology can extract information from invoices and receipts, while rules can categorise recurring transactions.
Automation can now assist with tasks such as:
- Importing Bank Transactions
- Matching Payments To Invoices
- Capturing Receipts Digitally
- Sending Recurring Invoices
- Sending Payment Reminders
- Calculating VAT
- Producing Financial Reports
- Processing Payroll Data
- Monitoring Outstanding Payments
- Preparing Information For Digital Tax Reporting
Artificial intelligence is also beginning to support transaction categorisation, document processing and financial administration.
However, automation has not removed the need for bookkeeping knowledge.
Software can categorise a transaction incorrectly. Duplicate transactions can appear. Personal expenditure may be confused with business costs. An expense may also have different tax treatment depending on why it was incurred.
Modern bookkeeping therefore combines technology with human review.
For many businesses, the question in 2026 is no longer whether bookkeeping is necessary. It is how much of the process can be automated and how much professional oversight is required.
Why Is Bookkeeping Important For Small Businesses?

Good bookkeeping gives business owners reliable financial information rather than forcing them to make decisions based on their bank balance alone.
A business may have money in its account but still have upcoming VAT, payroll, supplier or tax liabilities. Equally, a profitable business can experience cash flow problems when customers take too long to pay.
Accurate bookkeeping makes these issues easier to identify.
It can help small businesses:
- Monitor Cash Flow: See whether enough money is available to meet upcoming costs
- Track Profitability: Compare income with operating expenses
- Prepare Tax Information: Maintain the records needed for tax reporting
- Control Spending: Identify unnecessary or rising business costs
- Manage Debtors: See which customers owe money
- Manage Creditors: Track amounts owed to suppliers
- Prepare For Finance Applications: Produce organised financial information when lenders request it
- Identify Errors Early: Spot duplicate transactions, incorrect payments or missing invoices
- Plan Growth: Use financial information when considering recruitment, investment or expansion
Bookkeeping is therefore not simply an administrative obligation. When the records are current, they can become a useful management tool.
What Has Changed For Small Business Bookkeeping In 2026?
One of the most important developments in 2026 is the expansion of Making Tax Digital into Income Tax.
Making Tax Digital for Income Tax began applying from 6 April 2026 to qualifying sole traders and landlords whose qualifying income from self-employment and property exceeds the relevant threshold.
This increases the importance of keeping financial information digitally rather than assembling records shortly before the annual Self Assessment deadline.
The change does not mean every small business suddenly comes under the same rules.
Business structure, income and tax obligations still determine which requirements apply.
Who Needs To Follow Making Tax Digital In 2026?
From 6 April 2026, Making Tax Digital for Income Tax applies to individuals who meet the relevant conditions, including sole traders and landlords with qualifying income above £50,000, based on the required earlier tax return information.
The rollout is scheduled to expand further:
- From April 2026: Qualifying income above £50,000
- From April 2027: Qualifying income above £30,000
- From April 2028: Qualifying income above £20,000
Qualifying income broadly relates to gross income from self-employment and property before expenses.
Businesses should therefore avoid looking only at taxable profit when deciding whether the threshold affects them.
Making Tax Digital for Income Tax does not apply to every company or every source of personal income in the same way. Business owners should check the rules applying to their individual circumstances.
What Records Need To Be Kept Digitally?
Those required to use Making Tax Digital for Income Tax need compatible software for their digital records.
The system is designed around maintaining digital information about self-employment and property income and expenses and sending required updates to HMRC.
The software can be used to:
- Create Digital Records
- Store Income And Expense Information
- Correct Digital Records
- Prepare Quarterly Updates
- Submit Required Tax Information
Quarterly updates give HMRC summaries based on the digital records maintained during the year.
Businesses that are already within Making Tax Digital for VAT also have digital record-keeping requirements for VAT.
For affected businesses, bookkeeping is therefore becoming more closely integrated with tax administration.
What Records Must A Small Business Keep?
The exact records required depend on the business structure and taxes involved, but every business should be able to demonstrate where its income and expenditure came from.
A sole trader will generally need records covering areas such as:
- Sales And Other Business Income
- Business Expenses
- Sales Invoices
- Purchase Invoices
- Receipts
- Bank Statements
- VAT Records Where Applicable
- PAYE Records Where Employees Are Paid
- Relevant Personal Income Records
A limited company normally has wider accounting record requirements.
Company records can include:
- Money Received And Spent
- Company Assets
- Amounts The Company Owes
- Amounts Owed To The Company
- Stock Records
- Goods Purchased And Sold
- Invoices
- Receipts
- Bank Statements
- Contracts And Other Supporting Documents
Keeping only the total amount spent is not always enough. Businesses should retain supporting evidence that explains the transaction.
Digital copies can make this easier because receipts and invoices can often be attached directly to the relevant accounting entry.
How Long Should Small Businesses Keep Bookkeeping Records?
Record retention depends on the type of business and tax involved.
Sole Traders
Self-employed people normally need to retain their business records for at least five years after the 31 January submission deadline for the relevant tax year.
Records may need to be retained longer in certain circumstances, including where a return is submitted very late or HMRC is carrying out enquiries.
Limited Companies
Limited companies normally need to keep accounting records for six years from the end of the company financial year to which they relate.
Some records may need to be retained longer where, for example, they concern transactions covering more than one accounting period or HMRC has started a compliance check.
VAT Records
VAT records generally need to be retained for at least six years.
Rather than deleting information as soon as accounts have been completed, businesses should use a clear document-retention system.
Cloud storage can make this simpler, but businesses should ensure information remains accessible even if they later change accounting software or bookkeeping providers.
Should Small Businesses Use Cash Basis Or Traditional Accounting?
The correct method depends partly on business structure and circumstances.
From the 2024 to 2025 tax year, cash basis became the default accounting method for eligible sole traders and partnerships without corporate partners.
Under cash basis accounting, income is normally recorded when the business receives the money and expenses are recorded when they are paid.
For example, if a sole trader sends an invoice in March but the customer pays in April, the income is generally recorded when payment is received.
Traditional accounting works differently.
Under traditional accounting, transactions are generally recognised according to when income is earned or costs are incurred rather than simply when money moves.
Traditional accounting can be useful where a business:
- Carries Significant Stock
- Has More Complex Financial Arrangements
- Needs Detailed Year-End Adjustments
- Wants Accounts Suitable For Certain Finance Applications
- Needs To Track Debtors And Creditors Closely
Limited companies cannot use the Self Assessment cash-basis system in the same way as eligible sole traders.
Businesses should therefore choose an accounting approach based on their legal structure, complexity and reporting needs rather than assuming one method works for everyone.
What Bookkeeping Tasks Should Be Done Regularly?
Leaving all bookkeeping until the end of the year creates unnecessary work and makes errors more difficult to trace.
A regular routine can keep the records manageable.
Weekly Bookkeeping Tasks
Depending on the volume of transactions, weekly tasks may include:
- Record Sales And Expenses
- Upload Receipts And Purchase Invoices
- Issue Customer Invoices
- Check Incoming Payments
- Follow Up Overdue Invoices
- Review Bank Transactions
- Investigate Unrecognised Payments
- Keep Business And Personal Transactions Separate
Businesses with large transaction volumes may need to perform some of these tasks daily.
Monthly Bookkeeping Tasks
At least once a month, businesses should consider:
- Reconciling Bank Accounts
- Reconciling Credit Cards
- Checking Outstanding Customer Invoices
- Reviewing Supplier Balances
- Checking Payroll Records
- Reviewing Business Expenses
- Checking For Duplicate Transactions
- Reviewing Profit And Loss Information
- Looking At Cash Flow
- Correcting Misclassified Transactions
Monthly reconciliation is particularly important because it confirms that the records agree with the actual bank activity.
Quarterly Bookkeeping Tasks
Quarterly reviews may include:
- Reviewing Tax Liabilities
- Checking VAT Information Where Applicable
- Preparing Required MTD Updates
- Reviewing Financial Performance
- Checking Cash Flow Forecasts
- Reviewing Unpaid Debts
- Correcting Outstanding Bookkeeping Issues
The aim is to prevent bookkeeping problems from accumulating until the year end.
When Should A Small Business Get Bookkeeping Help?

Not every new business needs an external bookkeeper immediately.
A sole trader with a small number of straightforward transactions may be able to manage records independently using appropriate software.
Professional help becomes more useful as the business becomes busier or more complex.
Signs that bookkeeping help may be needed include:
- Records Are Several Months Behind
- Bank Reconciliations No Longer Match
- Receipts Or Invoices Are Frequently Missing
- VAT Has Become Difficult To Manage
- Payroll Is Taking Too Much Time
- The Business Has A Growing Number Of Transactions
- Several Bank Or Payment Accounts Are Being Used
- The Owner Does Not Understand The Financial Reports
- Tax Deadlines Are Becoming Difficult To Manage
- MTD Requirements Have Increased Administrative Work
- Bookkeeping Is Taking Time Away From Customers And Growth
A useful test is to compare the cost of professional help with the value of the owner’s time.
If a business owner spends several hours each week correcting transactions and organising receipts, outsourcing may become more economical than continuing to manage everything personally.
What Type Of Bookkeeping Help Does A Small Business Need?
Bookkeeping support does not have to mean employing somebody full time.
There are several levels of support.
DIY Bookkeeping
DIY bookkeeping may suit:
- New Sole Traders
- Freelancers
- Businesses With Few Monthly Transactions
- Owners Comfortable With Financial Administration
The main advantage is lower cost.
The disadvantage is that the owner remains responsible for keeping the system accurate and staying on top of deadlines.
Bookkeeping Software
Software can automate much of the repetitive administration.
It may suit businesses that can handle their own books but want to reduce manual work.
Useful functions may include:
- Bank Feeds
- Receipt Capture
- Invoice Creation
- Payment Tracking
- Bank Reconciliation
- Financial Reporting
- VAT Support
- MTD Compatibility
Software is a tool rather than a substitute for understanding the records.
Someone still needs to review exceptions and make sure transactions are treated correctly.
Outsourced Bookkeeper
An outsourced bookkeeper can manage routine financial records without the business employing a permanent member of staff.
Services may include:
- Transaction Recording
- Bank Reconciliation
- Sales Ledger Management
- Purchase Ledger Management
- Invoice Processing
- Payroll Support
- VAT Administration
- Financial Reporting
- Year-End Preparation
This option can suit growing small businesses that require regular support but do not need a full-time finance employee.
Accountant
An accountant may become more important where the business requires support beyond routine bookkeeping.
This can include:
- Annual Accounts
- Corporation Tax
- Complex Tax Matters
- Financial Planning
- Business Structuring
- Strategic Advice
- Complex Reporting
Bookkeepers and accountants often work together.
The bookkeeper maintains accurate day-to-day information, while the accountant can use those records for tax, accounts and higher-level financial work.
How Much Does Bookkeeping Help Cost For A Small Business?
Bookkeeping fees vary considerably across the UK.
As a broad market guide, basic bookkeeping may cost around £20 to £50 per hour, although prices can be higher depending on experience, location and the complexity of the work.
Many bookkeeping providers now charge fixed monthly fees rather than hourly rates.
The amount a business pays can depend on:
- Number Of Monthly Transactions
- Number Of Bank Accounts
- VAT Registration
- Payroll Requirements
- Number Of Employees
- Sales Platforms Used
- Currency Requirements
- Quality Of Existing Records
- Frequency Of Reporting
- Level Of Professional Support Required
A business with clean records and a few hundred straightforward transactions is likely to require less work than one with several bank accounts, ecommerce platforms, payroll and unreconciled records.
Catch-up bookkeeping can also cost more because the bookkeeper may need to reconstruct several months of transactions and find missing documents.
Businesses should compare quotes based on exactly what is included rather than choosing solely on the headline monthly price.
How Do You Choose A Reliable Bookkeeper In The UK?
A bookkeeper can have access to highly sensitive financial information, so price should not be the only consideration.
Businesses should check:
- Relevant Experience: Whether the bookkeeper understands businesses similar to yours
- Software Experience: Whether they can use the accounting platform used by the business
- VAT Knowledge: Whether the business is VAT registered
- Payroll Experience: Whether payroll support is required
- Professional Membership: Whether they belong to an appropriate bookkeeping or accounting body
- Qualifications: Whether their training matches the services they provide
- Anti-Money Laundering Supervision: Who supervises them for their professional compliance obligations
- Professional Indemnity Insurance: Whether appropriate cover is held
- Data Security: How financial information and login credentials are protected
- References and Reviews: Whether previous clients can demonstrate reliable service
- Pricing: Whether charges and additional fees are clearly explained
- Communication: How often the books will be updated and reports provided
Businesses should also clarify who owns the accounting software subscription and who will retain access to the financial records if the relationship ends.
The business should always be able to access its own financial information.
What Happens If A Small Business Does Not Keep Proper Records?
Poor bookkeeping can create problems long before HMRC becomes involved.
If records are incomplete, management reports may be unreliable. The business may believe it is more profitable than it actually is or may fail to notice customers who have not paid.
Possible consequences include:
- Incorrect Tax Returns
- Missed Tax-Deductible Expenses
- VAT Errors
- Late Payments
- Cash Flow Problems
- Duplicate Payments
- Unpaid Customer Invoices
- Difficulty Obtaining Finance
- Additional Accountant Fees
- HMRC Enquiries
- Penalties Where Legal Requirements Are Not Met
Limited companies have particularly clear accounting-record obligations.
Failure to maintain required company accounting records can potentially result in an HMRC fine of up to £3,000, and directors can face further consequences including possible disqualification.
Hiring an accountant or bookkeeper does not completely transfer responsibility away from the business.
Directors remain responsible for ensuring a limited company meets its legal responsibilities even when day-to-day accounting work is delegated.
This makes it important to review financial records regularly rather than assuming software or an external provider has automatically dealt with everything correctly.
Conclusion
Bookkeeping is not disappearing in 2026. It is becoming more digital, automated and closely connected with real-time financial management.
The basic purpose remains the same. Businesses need reliable records showing what they earn, what they spend, what they owe and what is owed to them.
For many small businesses, modern accounting software can reduce manual work significantly. However, technology still needs accurate data and sensible oversight.
The introduction of Making Tax Digital for Income Tax from April 2026 also means digital bookkeeping has become more important for affected sole traders and landlords.
A very small business may be able to manage bookkeeping independently. As transaction volumes increase, VAT, payroll, digital tax reporting and financial decision-making can make professional support increasingly valuable.
The right approach is therefore not to ask whether bookkeeping is outdated. Businesses should decide which parts they can manage efficiently themselves, which parts technology can automate and when professional bookkeeping help will save time or reduce risk.
Frequently Asked Questions
Do I Need A Bookkeeper For A Small Business?
Not every small business needs a bookkeeper. Businesses with simple finances may manage their own records, while growing or more complex businesses may benefit from professional support.
Can I Do My Own Bookkeeping?
Yes. Sole traders and small businesses can manage their own bookkeeping using suitable software, provided records are kept accurate and up to date.
Is Bookkeeping Still Important In 2026?
Yes. Bookkeeping remains essential for understanding income, expenses, cash flow, tax obligations and the overall financial position of a business.
Is Bookkeeping Becoming Automated?
Yes. Modern software can automate bank feeds, receipt capture, invoicing and transaction matching, although human review is still important for accuracy.
What Is The Difference Between A Bookkeeper And An Accountant?
A bookkeeper usually manages day-to-day financial records, while an accountant focuses more on accounts, tax, financial analysis and strategic advice.
Do Small Businesses Need Making Tax Digital In 2026?
Making Tax Digital for Income Tax applies from April 2026 to qualifying sole traders and landlords with qualifying income above £50,000, subject to the relevant rules.
How Often Should Small Business Bookkeeping Be Updated?
Bookkeeping should ideally be updated weekly or monthly rather than left until year end. Regular updates make errors, unpaid invoices and cash flow problems easier to identify.
Expert Blogger | Strategic thinker anticipating future directions for UK business
Related Articles in Business
View All →
Shell Petrol Station Franchise Cost in the UK: Real Investment, Income and Process
If you are searching for the Shell petrol pump franchise cost in the UK, the first thing to understand is that Shell does not currently advertise its UK…
Is Raising Cane’s Opening in the UK? | London Locations Revealed
Yes, Raising Cane’s is officially coming to the UK. The American chicken restaurant brand plans to open its first UK restaurant at 22 Coventry Street in London’s West…
Best Parking App UK: 10 Startup-Led Parking Apps Compared for 2026
For most drivers, JustPark is the best parking app UK users can consider in 2026 because it combines parking search, advance booking and app-based payments in one platform.…