How Long Does an Overdraft Take to Activate?

UK Startup Blog Archive
Table of Contents
An arranged overdraft may activate immediately after approval, although some banks take several hours or until the next working day to update the account. Applications requiring credit checks or manual assessment may take between two and ten working days.
Business overdrafts can take longer because the bank may need financial records, forecasts or security documents. The overdraft should only be used once the approved limit appears in the account’s available balance.
What Does Overdraft Activation Mean?
Overdraft activation is the point at which a bank adds an agreed borrowing limit to a current account. Once active, the account holder can spend more money than the account contains, up to the authorised limit.
For example, if an account has a balance of £100 and an active £500 arranged overdraft, the available balance may be £600. However, entering the overdraft means borrowing money and will usually result in interest charges.
An overdraft is different from a loan because there is no fixed borrowing amount or repayment schedule. Money can normally be borrowed, repaid and borrowed again while the facility remains available.
Businesses considering an overdraft should first ensure they have an appropriate business current account that supports borrowing facilities.
How Long Does an Overdraft Take to Activate After Approval?
The activation time depends on the bank, application method and type of account. A pre-approved personal overdraft requested through mobile banking may become available within minutes. A new application requiring further assessment can take several working days.
| Application situation | Typical activation time |
| Pre-approved offer accepted through an app | Immediately or within a few hours |
| Existing customer applying online | Same day to two working days |
| Application requiring a manual credit review | Three to ten working days |
| New current account with an overdraft | After the account and overdraft are both approved |
| Sole trader or small-business overdraft | Several working days to two weeks |
| Larger secured business overdraft | Two weeks or longer |
These are general timeframes rather than guaranteed deadlines. The bank’s own application process and the complexity of the applicant’s finances will determine the actual waiting time.
Can an Overdraft Be Used Immediately After Approval?
An overdraft can usually be used once the new limit appears in the account’s available balance. Receiving an approval message does not always mean the funds are immediately accessible.
The account holder should check:
- The arranged overdraft limit is displayed in online or mobile banking.
- The available balance includes the agreed borrowing amount.
- Any required agreement has been accepted.
- The activation date shown by the bank has arrived.
- There are no account restrictions or outstanding verification checks.
It is sensible to wait until the available balance has updated before making a payment. Spending before the facility becomes active could result in a declined transaction, unpaid payment fee or use of an unarranged overdraft.
Why Has an Approved Overdraft Not Activated Yet?
Several issues can delay activation even after an application appears to have been approved.
The Agreement Has Not Been Accepted
The bank may issue an offer that requires the customer to read and accept a credit agreement. The overdraft will not become active until this step has been completed.
The Account Has Not Updated
Banking systems do not always update immediately. An approved limit may take several hours to appear, particularly if the application was completed late in the day.
The Application Was Made at a Weekend
Automated approvals may still be processed outside normal banking hours, but applications requiring staff review may not progress until the next working day.
Identity Checks Are Outstanding
The bank may need additional proof of identity, address or business ownership before making the facility available.
A Credit Check Requires Review
An application can be referred for manual review because of the requested limit, recent credit activity, existing debts or inconsistent information.
Business Documents Are Missing
A business overdraft application may be delayed if the bank has not received recent accounts, tax returns, bank statements or cash-flow projections.
How Long Does a Business Overdraft Take to Activate?
A straightforward business overdraft for an existing customer may be approved and activated within a few working days. More complex applications can take one or two weeks, while secured or high-value facilities may take longer.
Banks commonly assess:
- How long the business has been trading.
- Recent account activity and average balances.
- Annual turnover and profitability.
- Existing loans and financial commitments.
- The reason the overdraft is required.
- The ability to bring the account back into credit.
- Credit histories of the business and its directors.
- Whether a personal guarantee or security is required.
Keeping clear small-business bookkeeping records can make it easier to provide the information needed during an application.
A bank may also request similar evidence to the documents covered under standard business loan requirements.
What Is the Overdraft Application Process?
The precise process varies between providers, but most applications follow several basic stages.
1. An Eligibility Check Is Completed
The applicant may be asked about income, regular expenses, employment or business turnover. Some banks initially use account activity or a soft credit search to estimate eligibility.
2. A Limit Is Requested
Applicants normally choose the amount they want to borrow. Requesting a significantly higher limit can lead to more detailed affordability checks.
3. The Bank Assesses Affordability
The bank reviews whether the account holder is likely to be able to manage the overdraft. This can include income, spending, existing borrowing and credit history.
For a business, the assessment may also include cash flow, profitability, trading history and future financial commitments.
4. An Offer Is Issued
If approved, the bank confirms the available limit, interest rate and important conditions. The offered amount may be lower than the amount originally requested.
5. The Agreement Is Accepted
The applicant must review and accept the overdraft terms. Some banks complete this electronically through online or mobile banking.
6. The Limit Becomes Active
The facility is ready to use when it appears as part of the account’s available balance.
What Can Make an Overdraft Application Take Longer?
An application is more likely to take longer when:
- The applicant has recently moved address.
- Income cannot be verified automatically.
- Several credit applications have been made recently.
- The requested limit is high in comparison with income.
- The account has a history of returned payments.
- Business ownership information is complicated.
- Financial accounts are incomplete or out of date.
- A personal guarantee requires separate documentation.
- Security must be valued or legally registered.
- Information on the application does not match bank records.
Responding promptly to requests for documents can prevent avoidable delays.
How Can Someone Check Whether an Overdraft Is Active?
The quickest method is usually to open the bank’s mobile application or online banking service and look for an overdraft section. It may show the arranged limit, amount currently used, remaining availability and interest rate.
The available balance may also provide confirmation. However, customers should not rely solely on a successful card transaction because some payments can be processed offline or appear later.
If the limit is not visible after the stated activation period, the account holder should contact the bank and ask:
- Whether the application has been fully approved.
- Whether an agreement still needs to be accepted.
- Whether any verification documents are outstanding.
- When the limit will appear in the available balance.
- Whether payments made before activation will be declined.
Does Applying for an Overdraft Affect a Credit Score?
An overdraft application may involve a credit search. Some eligibility checks use a soft search, which is not normally visible to other lenders. A full application may involve a hard search, which can appear on the applicant’s credit report.
Using an arranged overdraft does not automatically damage a credit score. However, remaining close to the limit, regularly exceeding it or having payments refused may suggest financial pressure.
For limited companies, a lender may consider both the company’s credit record and the personal credit histories of its directors.
Submitting several applications within a short period can make an applicant appear more dependent on credit. It is therefore worth checking eligibility before making repeated full applications.
How Much Does an Overdraft Cost?
Most UK overdrafts charge interest on the amount used rather than the full approved limit. Personal arranged overdrafts are commonly presented using an annual percentage rate, while business overdrafts may include interest and arrangement, renewal or monitoring fees.
For example, a customer with a £1,000 limit who uses £200 will normally pay interest on the £200 borrowed, not the unused £800. The actual cost depends on the interest rate and number of days the account remains overdrawn.
Business owners comparing business banking account options should examine overdraft charges alongside monthly account fees and transaction costs.
Is an Overdraft Suitable for Managing Cash Flow?
An overdraft can be useful for short-term cash-flow gaps, such as paying a supplier shortly before a customer invoice is received. It provides flexible access because interest is normally charged only when the facility is being used.
However, an overdraft may not be suitable for long-term borrowing. The bank can review the facility, reduce the limit or request repayment, subject to the agreement and any required notice.
A business relying on its overdraft every month may have a wider cash-flow problem. In that situation, reviewing costs, payment terms, late invoices and alternative finance could be more effective than repeatedly extending the limit.
Businesses can also compare business loan options when funding is needed for a longer period or a planned investment.
What Should Be Done if the Overdraft Is Needed Urgently?
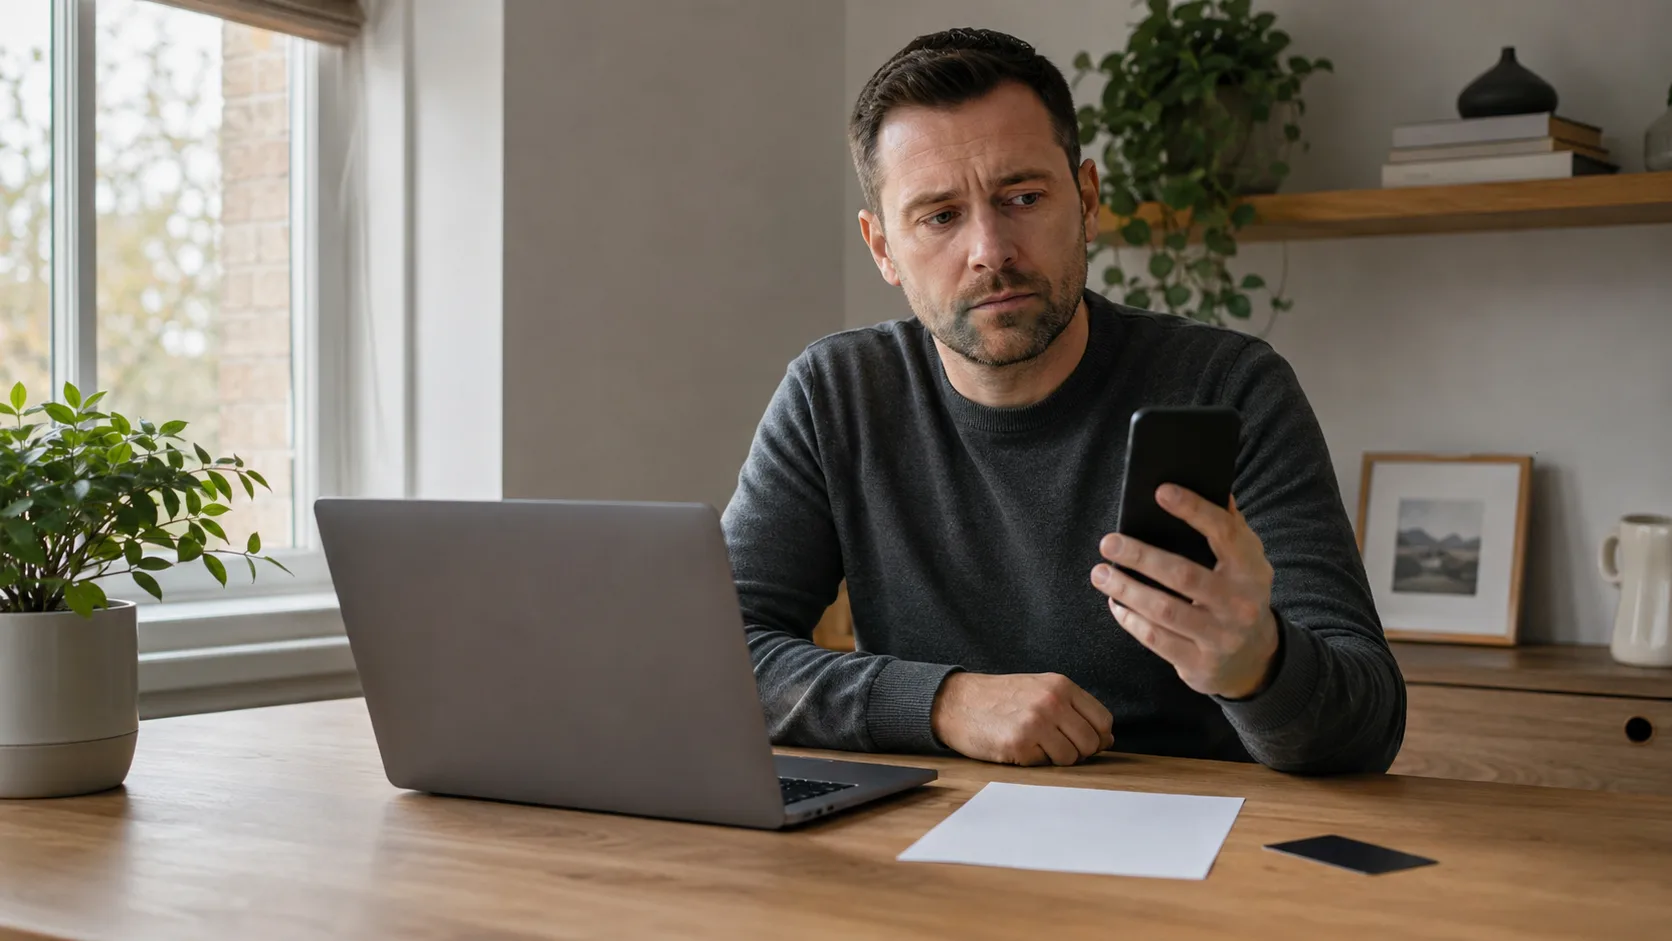
An applicant should not assume an overdraft will be available immediately. If a payment is due soon, it is worth contacting the bank before submitting the application to ask about likely assessment times.
To reduce delays:
- Apply during a working day where possible.
- Check that personal and business details are current.
- Request a realistic borrowing limit.
- Prepare recent statements and accounts.
- Respond quickly to verification requests.
- Read and accept the agreement promptly.
- Confirm activation before making payments.
If the application is still being reviewed, the applicant should not arrange transactions based on the expected overdraft.
Can a Bank Refuse or Withdraw an Overdraft?
Yes. An overdraft is a form of credit, so approval is not guaranteed. A bank may reject an application because of affordability concerns, poor account management, limited credit history or an excessive requested limit.
An existing overdraft can also be reviewed. Depending on the agreement, the bank may reduce or withdraw the facility and require the borrowed amount to be repaid. Overdrafts are therefore less predictable than borrowing with a fixed repayment term.
Account holders should review notices from their bank and avoid treating the overdraft limit as permanent income.
Final Thoughts
An overdraft can activate within minutes when a pre-approved offer is accepted, but some applications take several working days. Business overdrafts and applications requiring manual checks generally take longer.
Approval alone is not sufficient confirmation that the money is ready to use. The safest approach is to wait until the agreed limit appears in the account’s available balance.
Applicants should also check the interest rate, fees and repayment conditions before borrowing, as an overdraft is designed primarily for short-term financial flexibility.
Frequently Asked Questions
How long does an overdraft take to show in an account?
A pre-approved overdraft may show immediately, while another approved facility may take several hours or until the next working day. Manual applications can take longer.
Why does my overdraft say approved but not available?
The bank may still be updating the account, waiting for acceptance of the agreement or completing final verification. The overdraft should not be used until it appears in the available balance.
Will an overdraft activate at the weekend?
Some automated applications can activate at weekends. Applications requiring a manual review may not be processed until the next working day.
Can I withdraw cash as soon as my overdraft is active?
Normally, yes, provided cash withdrawals are permitted and the available balance includes the overdraft. Daily cash-machine limits will still apply.
Does opening a new account delay an overdraft?
It can. The bank may need to complete identity, address and account-opening checks before assessing or activating the overdraft.
How long does an overdraft increase take?
A pre-approved increase may be immediate. A requested increase requiring new affordability and credit checks could take several working days.
Is an unarranged overdraft activated automatically?
No. An unarranged overdraft is not an approved credit limit. It occurs when a payment takes an account beyond its balance or arranged limit, and the bank may decline the payment instead.
Blogger | Business Writer | Sharing startup advice on UK business blogs
Related Articles in Finance
View All →
If I Take Home £1,600 a Month, What Is My Salary in the UK?
If an employee takes home £1,600 per month in the UK, their estimated gross salary is approximately £21,780 per year. This is equal to about £1,815 per month…
Why the Two Year Accounts Rule is Not Actually a Rule?
Ask most new business owners when they can first apply for a mortgage and the answer comes back the same way every time: two years of accounts, minimum,…

Snap-on Franchise Cost: Fees, Investment and Earnings
The Snap-on franchise cost in the UK is currently quoted at £166,597 to £168,487 for the franchise investment, with Snap-on stating that a new franchisee may need to…