What Happens When You Report Someone to HMRC? 2027 Guide

UK Startup Blog Archive
Table of Contents
When you report someone to HMRC for suspected tax evasion, undeclared income or business tax fraud, HM Revenue and Customs assesses the information and decides whether further checks are necessary.
It may examine tax records, request financial information or launch an investigation. However, reporting someone does not automatically result in an investigation, a fine or criminal prosecution.
You can report suspected wrongdoing anonymously, and HMRC treats information supplied by informants as confidential. You should not expect to receive updates about the investigation.
Our analysis of HMRC’s latest procedures and 2026 enforcement figures highlights an important distinction: reporting suspicious financial activity provides intelligence, but HMRC must establish the facts before taking enforcement action.
What Actually Happens After You Report Someone to HMRC?
HMRC does not automatically send investigators to someone’s home or business after receiving a tip-off. Information is assessed before the department determines what action is appropriate.
The process can involve several stages:
| Stage | What HMRC May Do |
| 1. Report received | Record the information about suspected tax fraud |
| 2. Initial assessment | Consider its relevance, credibility and possible tax implications |
| 3. Information checks | Compare allegations with tax returns and other available records |
| 4. Further enquiries | Request information or begin a compliance check if justified |
| 5. Outcome | Close the matter, recover unpaid tax, impose penalties or investigate serious fraud |
These are possible stages, not a guaranteed sequence for every report.
For example, if someone reports a self-employed contractor who allegedly receives £40,000 annually in undeclared cash payments, HMRC may assess the allegation against information already held about that individual.
The situation is different if somebody has simply misunderstood the rules around self-employed income. Not every payment is taxable, and not every reporting error is deliberate fraud.
Does HMRC Investigate Every Report It Receives?
HMRC assesses reports, but not every allegation leads to a formal investigation.
According to its 2025–26 annual report, HMRC received 170,992 reports alleging tax non-compliance and conducted approximately 306,000 compliance checks during that financial year.
These figures demonstrate the scale of its compliance work, but they do not mean that 306,000 investigations resulted from public tip-offs. They measure different activities.
Whether a particular report progresses can depend on the information provided, the potential tax risk and HMRC’s existing intelligence.
From a business perspective, our findings suggest that a specific allegation involving dates, transactions and identifiable individuals provides a clearer basis for assessment than a general accusation without supporting details.
Consider these examples:
- Cash businesses: A restaurant allegedly records only some cash transactions.
- Payroll irregularities: An employer reportedly pays workers without properly accounting for PAYE.
- Online trading: A seller runs a trading business but may not declare taxable profits.
- Property income: A landlord allegedly conceals taxable rental income.
- Company transactions: Directors may be using inaccurate financial records to understate taxable profits.
Importantly, receiving cash or selling products online does not itself establish tax fraud. For example, the rules concerning Vinted tax distinguish ordinary personal-item sales from taxable trading activities.
Will Someone Know You Reported Them to HMRC?
One of the biggest concerns when reporting suspected tax evasion is whether the person involved will discover who submitted the information.
HMRC allows anonymous reporting and treats identifying information supplied by reporters as private and confidential.
You do not have to provide your name, address or telephone number when submitting a standard tax-fraud report.
However, confidentiality should not be confused with an absolute guarantee that nobody could ever guess the source of an allegation.
For example, if a former employee reports financial irregularities known to only a small number of colleagues, the business owner might speculate about who contacted HMRC.
Our assessment is that providing information anonymously can reduce the amount of identifying information held about you, while supplying contact details allows HMRC to request clarification when necessary.
You should avoid discussing the report publicly or confronting the person involved.
How Can You Report Someone to HMRC in 2027?
The official process is straightforward. You can report suspected tax fraud through the HMRC tax fraud reporting service.
The service covers suspected tax evasion, certain avoidance arrangements, undeclared business income, Child Benefit or tax credit fraud, and other specified customs and tax offences.
To make a report:
- Open the GOV.UK reporting service.
- Select the option to start an online report.
- Describe the suspected wrongdoing accurately.
- Provide identifying details and relevant dates where known.
- Decide whether to provide your own contact information.
- Submit the report and retain any confirmation provided.
If you cannot use the online form, HMRC’s fraud hotline is 0800 788 887, available Monday to Friday, 9am to 5pm, excluding bank holidays.
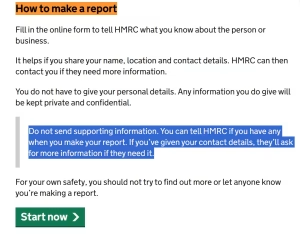
Official GOV.UK tax fraud reporting page showing the reporting options, confidentiality guidance and online reporting button.
What Information Should You Include?
The most useful reports explain what may have happened, who was involved and how the person reporting became aware of the issue.
Include information you already know, such as business names, relevant dates, the suspected activity and approximate amounts where these can reasonably be estimated.
HMRC advises against submitting supporting documents through the initial form. You can explain what records already exist, and HMRC may ask for more information later.
Do not conduct your own investigation, unlawfully access records or try to obtain private financial information.
We developed the following simple editorial checklist to help readers assess whether their report is sufficiently clear.
| Information Provided | Editorial Completeness Score |
| Person or business identified | 20% |
| Suspected activity described | 20% |
| Relevant dates or locations | 20% |
| Explanation of how you know | 20% |
| Available financial details or records described | 20% |
| Maximum | 100% |
This is our own information-completeness checklist, not an HMRC scoring system. An 80% or 100% score does not indicate the probability of investigation or prosecution.
What Happens If HMRC Finds Tax Evasion?
Where HMRC identifies unpaid tax or inaccurate records, the consequences depend on the facts, the applicable legislation and whether the conduct was careless or deliberate.
| Possible Outcome | Business or Financial Consequence |
| No wrongdoing identified | No further enforcement action may be necessary |
| Accounting error discovered | Corrections to tax records or returns |
| Unpaid tax identified | Additional tax and potentially interest |
| Careless inaccuracies | Financial penalties may apply |
| Deliberate tax evasion | Potentially higher penalties and specialist investigation |
| Serious criminal fraud | Possible prosecution and other criminal sanctions |
HMRC commonly uses civil procedures for tax non-compliance, while criminal investigations may be appropriate in particularly serious cases.
For employers, suspicious PAYE practices can create liabilities beyond the original unpaid tax, particularly where wages have not been properly recorded.
Small business owners should also ensure their tax returns reflect their actual trading activity and are supported by reliable bookkeeping.
A key finding from our review is that poor record keeping and deliberate concealment should not be treated as identical. HMRC considers behaviour, disclosure and cooperation when determining potential penalties.
How Long Does HMRC Take to Investigate Someone After a Report?
There is no fixed investigation timetable for public tax-fraud reports.
Some information may be assessed without progressing to a formal enquiry. Complex cases involving multiple businesses, offshore structures or extensive financial records can take considerably longer.
HMRC’s guidance for serious tax-evasion reports acknowledges that investigations can take years to conclude.
This means you should not assume that a person has escaped scrutiny simply because no visible action follows your report.
You should also not expect HMRC to confirm whether an investigation has started.
Under the serious tax-evasion reporting process, HMRC advises against sending repeated reports about the same activity or contacting the department for progress updates. It may contact you if further information is needed.
Can You Get a Reward for Reporting Tax Evasion in 2027?
One of the most significant developments affecting HMRC whistleblowers was the introduction of the Strengthened Reward Scheme on 26 November 2025.
Under the scheme, eligible individuals who provide information leading HMRC to collect at least £1.5 million in unpaid tax may receive a reward.
The potential reward is between 15% and 30% of the additional tax collected, excluding penalties and interest.
However, the payment is discretionary and is not guaranteed.
The scheme is primarily relevant to substantial tax avoidance or evasion, which can involve large companies, wealthy individuals and offshore arrangements.
Importantly, anonymous reporters are ineligible for a reward under this scheme, even though HMRC accepts anonymous reports.
The full eligibility conditions are explained in the official HMRC reward scheme guidance.
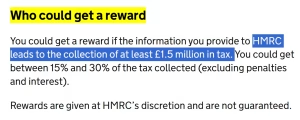
HMRC’s Strengthened Reward Scheme explains the £1.5 million recovery threshold and potential 15%–30% informant reward.
Our financial assessment is that the reward scheme should not be confused with ordinary reporting of a neighbour, small trader or local business. A report involving minor undeclared income is unlikely to meet its high-value recovery threshold.
What Should You Do If Someone Reports Your Business to HMRC?
Being reported is not proof of wrongdoing. A business owner may not even know that a report has been submitted unless HMRC makes contact.
If HMRC opens a compliance check, it will generally explain what it intends to examine and what records it requires.
Business owners should respond professionally, preserve existing accounting information and obtain qualified tax advice where necessary.
Practical steps include reviewing:
- Business sales, invoices and bank reconciliations.
- PAYE records and employee payments.
- VAT and Corporation Tax returns, where applicable.
- Self Assessment records and declared trading income.
- Transactions involving directors and connected businesses.
Accurate bookkeeping is especially important as Making Tax Digital expands to more eligible sole traders and landlords from April 2027.
If errors are identified, correcting them voluntarily can be financially important. HMRC’s October 2026 voluntary disclosure guidance explains that disclosing unpaid tax before HMRC contacts you will usually result in lower penalties than waiting to be approached.
An individual who has both employment and freelance income should also understand the rules for being employed and self-employed, rather than assuming employment tax deductions cover every source of income.
Our assessment: The strongest response to an HMRC enquiry is accurate documentation, timely cooperation and professional advice—not confrontation with anyone suspected of making a report.
Conclusion
Reporting someone to HMRC can result in an assessment, compliance check or serious tax investigation, but not every report leads to enforcement action.
For 2027, the most important points remain confidentiality, accurate reporting, realistic expectations and the distinction between suspected wrongdoing and proven tax fraud.
Our analysis of the 2026 updates also shows that HMRC’s strengthened whistleblower reward scheme introduces a potentially significant financial incentive for eligible high-value reports, while ordinary reporting remains available anonymously.
For taxpayers and business owners, maintaining accurate records and addressing mistakes early remains the most effective way to reduce avoidable HMRC compliance risks.
Frequently Asked Questions
Can I report someone to HMRC without proof?
Yes. You can report a genuine suspicion without proving that fraud occurred. Explain what you know and distinguish facts from assumptions. HMRC decides whether further investigation is justified.
What happens if you falsely report someone to HMRC?
An incorrect allegation does not automatically result in penalties against the reporter. A mistaken report made in good faith differs from a deliberately malicious or knowingly false accusation, which may create legal risks depending on the circumstances.
Can HMRC check bank accounts after receiving a report?
HMRC has statutory information-gathering powers that can include obtaining relevant financial information, subject to applicable legal conditions and safeguards. A tip-off does not automatically authorise unrestricted access to someone’s bank accounts.
Can you report someone for working cash in hand?
Yes, if you genuinely suspect undeclared taxable income. However, cash payments are legal when the relevant tax obligations are met. Cases involving undeclared work and benefit claims may also require a separate benefit fraud report.
Will HMRC tell me the outcome of my report?
Generally, no. HMRC does not ordinarily provide informants with investigation updates or disclose confidential information about another taxpayer’s affairs.
Can HMRC investigate a limited company following an anonymous report?
Yes. HMRC may assess anonymous information about suspected company tax irregularities and undertake appropriate enquiries if justified. An anonymous report does not automatically establish that a company has broken the law.
Blogger | Business Writer | Sharing startup advice on UK business blogs
Related Articles in Startup
View All →
Newscivil Com: Can This Digital News Platform Help UK Startups Spot Emerging Trends?
For startup founders, staying informed is no longer simply about reading the business pages each morning. Artificial intelligence, changing consumer habits, technology developments, government decisions and wider social…
Meet the Startup Turning Screen Time Into a New Way to Make Money
Britain does not exactly have a shortage of side hustles. You can deliver takeaways, sell clothes online, start freelancing, walk dogs, tutor in the evenings or attempt to…
8 Best Coworking Spaces for Bootstrapped London Startups to Launch and Scale in 2026
Bootstrapped founders don’t have the luxury of a fitted-out HQ from day one. What you need is a London coworking space that flexes with you: a hot desk…